Five-Minute Win
This week's Five-Minute Win: Calculate your FI number.
Take your annual spending and multiply it by 25.
That's it.
If your household spends $60,000 per year, your rough FI number is $1.5 million. Spend $80,000 and it's $2 million.
Obviously, your actual FI plan can get much more detailed than that. Social Security, pensions, taxes, healthcare, withdrawal strategies, and dozens of other variables can all matter. But that's not the point of this exercise.
I suspect a surprising number of people interested in financial independence have never actually calculated the number they're working toward. And even if you did years ago, when was the last time you updated it based on what your life costs today?
You don't need a spreadsheet with 47 tabs. Start with the simplest possible estimate: annual spending × 25.
Take five minutes today. Your future self will be glad you did.
VTSAX Is Not the Point
I saw another post this week from someone who owns VTSAX in a brokerage account outside of Vanguard, and I feel like I need to stand on a hill and scream about this.
There is nothing magical about VTSAX.
For years in the FI community, VTSAX became shorthand for simple, low-cost index investing. That's great. The problem is that somewhere along the way, some people seem to have gotten the message that they actually need to own VTSAX.
They don't.
If you're buying another company's mutual fund through your brokerage, you may be getting hit with a significant transaction fee every time you buy. Fidelity, for example, currently charges $49.95 for most online purchases of transaction-fee non-Fidelity mutual funds. At Schwab, the fee can be as high as $74.95.
Imagine you're at Fidelity and investing $500 each month into a Vanguard mutual fund that carries the standard $49.95 transaction fee. You're losing almost 10% of every contribution before your money is even invested. That's an incredible price to pay because someone told you VTSAX was the fund you were supposed to own.
So, here's my rule of thumb: Don't pay a transaction fee to buy one firm's mutual funds at another brokerage.
If you're at Fidelity, look for the low-cost Fidelity equivalent. If you're at Schwab, look for the low-cost Schwab equivalent. There is nothing special about the Vanguard name.
And if you really want a particular Vanguard fund but keep your investments somewhere else, look at the ETF version instead. VTI, for example, gives you Vanguard's total stock market exposure in an ETF, and online ETF trades are generally commission-free at Fidelity and Schwab.
We spent years telling people to “buy VTSAX” because it was an easy way to explain a much bigger idea. But the bigger idea was never to own one particular mutual fund.
It was: Own the market. Keep your costs incredibly low. Get out of the way.
And if you're paying $49.95 or $74.95 every time you buy your favorite low-cost index fund, you've missed the point entirely.
A Few Things...
A few things I found interesting this week...
🚗 AutoSlash
Erin was looking for a rental car this week when I asked, “Did you check AutoSlash yet?”
She had never heard of it.
I've been using AutoSlash for years and assumed most people knew about it. You enter the details of your trip and it searches through rental-car rates, coupons, and discounts to find a good price.
Rental-car prices move around constantly, so you can give AutoSlash your existing reservation and have it keep checking the price for you. If it finds a better deal, it'll email you and you can rebook at the lower rate. I've saved a surprising amount of money over the years doing exactly this.
The service is free, and I especially like that it does something I would never remember to do myself: keep checking the price of a rental car I've already booked.
There are probably other similar services, and for this particular trip to New Hampshire, AutoSlash didn’t have a price that would beat Turo, but it’s still my go-to starting spot for car rentals.
❤️ Pay Attention
I had a health surprise recently when I was diagnosed with atrial fibrillation. Luckily, I’m absolutely fine and this isn’t a huge deal at the present moment, but it was still a good reminder that you never really know when something unexpected is going to come up with your health.
I spend a lot of time thinking about staying fit and healthy so I can have as many good years as possible. This was a useful reminder that part of taking care of yourself is noticing when something changes, getting it checked out, and then dealing with what's actually there.
I bought a KardiaMobile, a tiny device that lets me take an ECG with my phone and save the results to share with my doctor. I've also been looking more closely at the trends I've accumulated over years of wearing my WHOOP, and it was interesting to see the odd results the two times I’ve been in AFib and to have that data to show the doctor.
I'm hesitant to recommend any particular health device or tracker because what makes sense for me isn't necessarily going to make sense for everyone. But I have found it useful to have years of data showing what “normal” looks like for me. When something suddenly looks very different, that's probably worth paying attention to.
🤖 How Smart People Are Using AI
I listen to a ridiculous number of podcasts, but rarely recommend individual episodes here. This one from My First Million was worth sharing.
Sam Parr and Shaan Puri talked with Wade Foster, the founder of Zapier, about how he's actually using AI in his day-to-day life. He has AI helping prepare morning and evening briefs, uses different AI perspectives to argue through decisions, and even showed how he's using it to improve hiring.
What I found most useful wasn't necessarily any one tactic. It was seeing how someone incredibly successful and productive is experimenting with these tools.
Some of the smartest people I know are doing the same thing. Frank Vasquez and Dr. Bobby Dubois from our community immediately come to mind. I'm using AI dozens of times a day myself, and I'm constantly finding new things to try.
You certainly don't need to use AI exactly the way Wade does. But right now I'm fascinated by seeing how really smart, productive people are actually using these tools. Every time I have one of these conversations, I come away with three or four things I want to try myself.
🧂 Our Homemade LMNT
I've mentioned this before somewhere, either in the newsletter or on the podcast, because people occasionally write to ask me for the recipe.
I really like LMNT, and one of the most surprising things about the company is that they actually publish the recipe for their electrolyte mix. They believe strongly enough in the convenience and taste of their product that they're perfectly happy to tell you how to make it yourself and essentially dare you to do it.
Needless to say, we took them up on that dare.
Using an inexpensive food scale, we now make 30 servings at a time by mixing 75 grams of salt, 11.5 grams of potassium chloride, and 11.7 grams of magnesium malate in a jar. Cover it, shake everything together thoroughly, and you're done. (I usually make 60 servings at once because, why not?)
When we want a glass, we measure out a serving and add a little stevia and lemon juice. It isn't quite as tasty as an individually flavored LMNT packet, but it's pretty fantastic considering it costs us only a few pennies per serving instead of more than a dollar for the “real” LMNT.
The Anti-Lemming Strategy
There's another slightly ridiculous phrase my daughters have heard from me for years: the anti-lemming strategy.
The basic idea is simple. Whenever everyone else is doing the same thing at exactly the same time, I ask whether there's any reason we need to be doing it then too.
Our community pool is a perfect example. We love going to the pool all summer, but there are three days I have almost no interest in being there: Memorial Day, the Fourth of July, and the member appreciation party. Those are the days when everyone suddenly decides they absolutely have to go to the pool and it’s swamped with people.
We can go on any of the other days and not have to fight for chairs or deal with a packed pool.
I think about Valentine's Day and Mother's Day the same way. They're two of the busiest restaurant days of the year. Instead of celebrating with dinner on the exact night everyone else is trying to do the same thing, why not go the day before or the day after? The celebration doesn't become less meaningful because the calendar says February 13 instead of February 14.
The point isn't to avoid popular things or to be different simply for the sake of being different. It's to notice when you're accepting a worse experience solely because everyone else has agreed that this is when you're supposed to do it.
Once you start looking for this, you see it everywhere. Travel dates. Restaurants. Amusement parks. Shopping. Even what time you drive somewhere.
Sometimes there's a good reason everyone is doing the same thing at the same time. But when there isn't, I'm perfectly happy to let the lemmings go first.
Around ChooseFI
A few things happening around the ChooseFI community...
🎉 Community Wins
One of the most-loved parts of the newsletter is the ChooseFI Community Taking Action section, and it only continues to exist because you share your wins. Hit reply to this email and send in your win.
📍 Local Groups
If you haven't already, take 30 seconds to join your local ChooseFI group. You'll automatically receive email notifications about meetups and events in your area, making it easy to connect with other people on the path to FI.
Rob, one of our admins in Phoenix, posted this after their latest meetup:
“We had nearly 70 members of the ChooseFI community join us this morning for a wonderful “FI 201” discussion! Love seeing this community continue to grow and so much wisdom and kindness was shared during today’s meetup.”
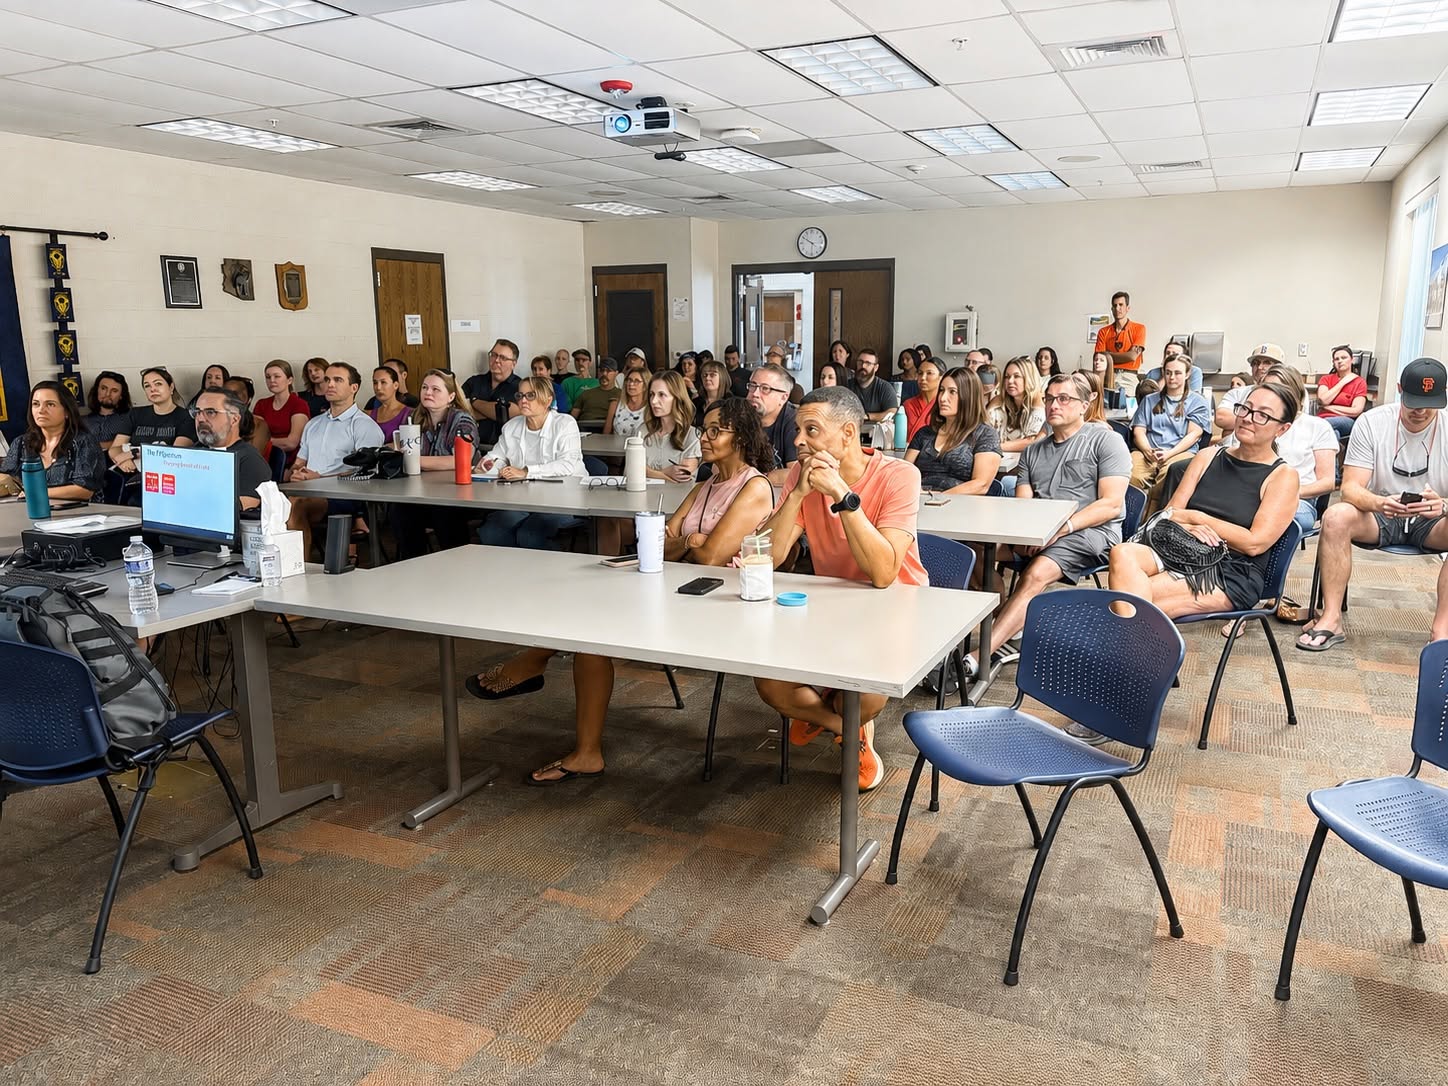
I'm blown away by how many local group events I'm seeing with 50+ people. It's a testament to our incredible Local Admins and the strength of this community.
🎙️ Continue the Conversation
Have thoughts or questions about this week's podcast? Join the discussion on Episode 615, where I have a far-ranging conversation with Fritz Gilbert on learning to spend money and how to get more years of freedom out of FI.
✈️ Travel Rewards
My Top Ten Recommended Travel Rewards Cards page is always up to date, including current welcome offers. If you're thinking about your next travel rewards card, that's the first place I'd look.
If you apply using our links, ChooseFI earns a commission at no additional cost to you. This is how we're able to keep the podcast and newsletter ad free. For nearly a decade, we've made the deliberate choice not to interrupt the podcast with traditional ad breaks, and I'd love to keep it that way. If you're going to apply for one of these cards anyway, using our link gets you the same offer, costs you nothing extra, and helps us keep ChooseFI ad free. We're incredibly grateful.