Five-Minute Win
This week's Five-Minute Win: Step outside within an hour of waking up.
Spend 5+ minutes outside tomorrow morning. If you've listened to Dr. Andrew Huberman's podcast, you've probably heard him talk about morning sunlight as one of the simplest ways to set your circadian rhythm and help your body know when it's time to sleep later that night.
I try to take a 15-minute walk each morning, which lets me get some steps in while getting that morning light.
Be Conservative Intentionally
I've noticed something interesting when talking with people who are getting close to financial independence.
They'll start with the 4% rule, but decide that's a little too aggressive, so they'll use 3.5% instead. Then they'll assume their investments will earn significantly less than historical averages, just to be safe. They'll estimate that their spending in retirement will be higher than it is today. They won't count Social Security because they don't trust that it'll be there. And then they'll keep a couple of years of expenses sitting in cash in case the market crashes.
Let’s be clear: every margin of safety has a cost.
If you assume higher expenses, lower returns, a lower withdrawal rate, no Social Security, and a large cash buffer all at once, you can create a financial plan designed to survive a future that's dramatically worse than almost anything we've historically experienced.
That's certainly safe. But it might also tell you that you need another $500,000 before you can retire. And if saving that additional money takes another three or five years, the margin of safety wasn't free. You paid for it with three or five years of your life.
I'm not arguing that we should build financial plans with no margin for error. But if I’m going to be conservative, I want to be conservative intentionally.
If I'm using a lower safe withdrawal rate, what risk am I protecting against? If I'm also assuming unusually poor investment returns, am I protecting against a different risk, or have I just accounted for the same bad market twice? If I'm ignoring Social Security entirely, what am I assuming happens to it? If I've already built plenty of flexibility into my spending, do I need another enormous buffer on top of that?
The goal isn't to create the most conservative spreadsheet possible. The goal is to build a plan that gives you enough confidence to actually use it.
A Few Things...
A few things I found interesting this week...
✈️ PointsYeah Daydream Explorer
Most of us search for flights by deciding where we want to go and when we want to go, and then trying to find a decent flight to make it happen.
But what if you don't really care where you go?
That's why I love PointsYeah's Daydream Explorer. Instead of searching Richmond to Paris on a particular week, I can essentially tell it: Here are the airports I'm willing to leave from. Show me where I can go with my points.
From there, you can filter for things like business class, the points programs you have access to, how many points you're willing to spend, taxes and fees, number of stops, and even how many seats you need.
And this is where FI flexibility becomes a real travel advantage. If I don't really care whether my next trip is to Amsterdam, Copenhagen, or Madrid, I'd much rather see where there's an incredible points deal and let that help determine the trip.
I've been using PointsYeah for years, and somehow when I first wrote about Explorer I buried one of the coolest ideas in travel rewards: Instead of deciding where to go and then searching for an award, sometimes it's more fun to find the amazing award and let that decide where you go.
🧾 Check Your Social Security Record
I saw a post from The FIRE Playbook listing websites retirees should bookmark, and one of them prompted me to do something useful: log into my Social Security account at SSA.gov.
It takes just a few minutes, and there are two things worth checking.
First, look through your earnings history. Social Security has a year-by-year record of the income credited to you, and those numbers ultimately feed into your benefit calculation. It’s worth making sure nothing looks obviously wrong or missing.
Second, take a look at your personalized retirement estimates at different claiming ages. One consideration for the FI community: you can adjust your expected future earnings in their calculator. If you’re planning to stop working early or substantially reduce your income, that may give you a more realistic estimate than assuming you’ll continue earning at your current level.
A genuinely useful five-minute financial check.
🎮 StarCraft Is Still Ridiculously Good
I’ve been playing the original StarCraft again lately, a game I loved back in college and have returned to off and on for years.
I’m reminded every time I play how demanding it is cognitively. You’re gathering resources, building units, expanding your base, scouting, defending, attacking and constantly deciding what deserves your attention next. It feels like I’m making dozens of tiny decisions every minute.
I don’t know whether it technically qualifies as “brain training,” but it certainly feels that way to me. I have to stay focused, make quick decisions and constantly adjust when my carefully constructed plan falls apart.
Mostly, though, it’s just incredibly fun and challenging.
🎓 A Student Loan Deadline Worth Knowing
I talked with Travis Hornsby from Student Loan Planner on the podcast recently, and one deadline is worth knowing:
If you have a Federal Direct Loan originated after July 1, 2012, enrolling in autopay by September 30 can reduce your interest rate by 1 percentage point through June 30, 2028, instead of the normal 0.25% autopay discount.
If you're already enrolled in autopay, you don't need to do anything. The increased discount should happen automatically.
A full percentage point isn't insignificant. On a $50,000 student loan balance, that's roughly $500 of interest per year before accounting for the declining balance.
If you have federal student loans, it's worth checking before September 30.
💰 Expectations Are a Liability
Sahil Bloom said something on the Afford Anything podcast that I've never thought about quite this way before:
“Expectations are your single greatest financial liability. If your expectations rise faster than your assets, you will never feel wealthy. You will never be rich. Because you'll just be chasing whatever more you convince yourself will lead to your future happiness.”
We spend decades accumulating assets, but if every increase in income and net worth is accompanied by an increase in what we believe a wealthy life is supposed to look like, the finish line keeps moving.
This Company or the Field?
Years ago, I used to religiously watch Pardon the Interruption on ESPN, and they had a question that I've always loved:
This team or the field?
Would you take one team to win the championship, or every other team combined?
It's such a simple question, but I’ve come to use it all the time when thinking about probabilities in investing and life.
Let’s look at Tesla.
Whatever you think of the company or Elon Musk, Tesla's accomplishments to this point are extraordinary. It helped force the automobile industry toward electric vehicles and became the dominant name in the category. If you recognized that possibility early, you were spectacularly rewarded.
But investing is always about what happens next.
Tesla's valuation today depends on much more than selling cars. A significant part of the story is what Tesla might become in autonomous driving, humanoid robotics, AI, energy, and other enormous future markets.
Instead of asking whether Tesla can succeed in those industries, I've started asking the old PTI question:
Tesla or the field?
In autonomous driving, would you rather bet on Tesla, or Waymo and every other company in the world working on autonomy?
In humanoid robotics, would you rather bet on Tesla's Optimus, or Unitree, Figure, Boston Dynamics, the rapidly growing Chinese robotics industry, and everyone else who will enter the market over the next twenty years?
Even in electric vehicles, where Tesla has already been wildly successful, I'd take the field. If Tesla still controlled 15% of the entire global automobile market twenty years from now, that would be an astonishing accomplishment. It would also mean the field controlled 85%.
The current valuation seems to require extraordinary success across several of these categories. If you use The Field Test, that seems unbelievably unlikely.
The Field Test is useful far beyond Tesla of course:
When an investment thesis requires a company to dominate an enormous future market, you need to compare it with everyone else in the world combined. And know that those companies aren’t sitting still waiting for this presumptive winner to take a bow.
Around ChooseFI
A few things happening around the ChooseFI community...
🎉 Community Wins
One of the most-loved parts of the newsletter is the ChooseFI Community Taking Action section, and it only continues to exist because you share your wins. Hit reply to this email and send in your win.
📍 Local Groups
If you haven't already, take 30 seconds to join your local ChooseFI group. You'll automatically receive email notifications about meetups and events in your area, making it easy to connect with other people on the path to FI.
Marina, one of our admins in LA, posted this after their latest meetup:
“Investor Policy Statements in the books… this will be a continued conversation in future meetings…”
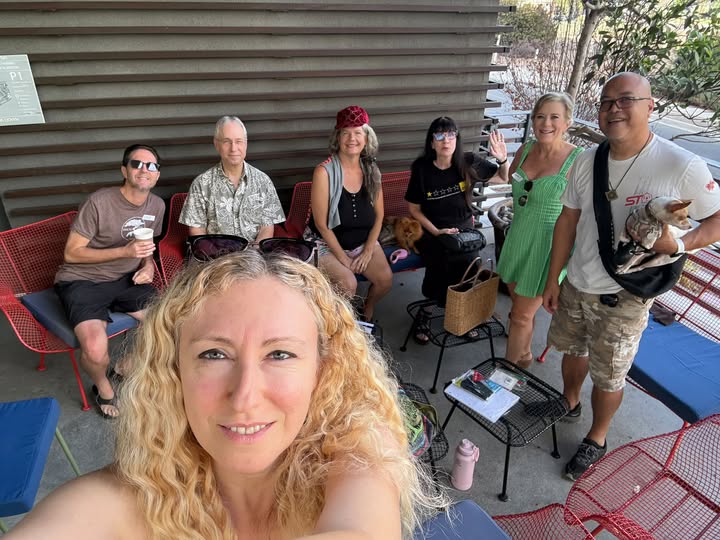
I loved this. They turned the meetup into a brainstorming and accountability session around their own investor policy statements.
🎙️ Continue the Conversation
Have thoughts or questions about this week's podcast? Join the discussion on Episode 616, where Sean Mullaney, Cody Garrett, and I talk about the many different ways to give money and invest for your children. This was an important episode, and Sean and Cody will be in the comments answering your questions.
✈️ Travel Rewards
My Top Ten Recommended Travel Rewards Cards page is always up to date, including current welcome offers. If you're thinking about your next travel rewards card, that's the first place I'd look.
If you apply using our links, ChooseFI earns a commission at no additional cost to you. This is how we're able to keep the podcast and newsletter ad free. For nearly a decade, we've made the deliberate choice not to interrupt the podcast with traditional ad breaks, and I'd love to keep it that way. If you're going to apply for one of these cards anyway, using our link gets you the same offer, costs you nothing extra, and helps us keep ChooseFI ad free. We're incredibly grateful.