Key Takeaways
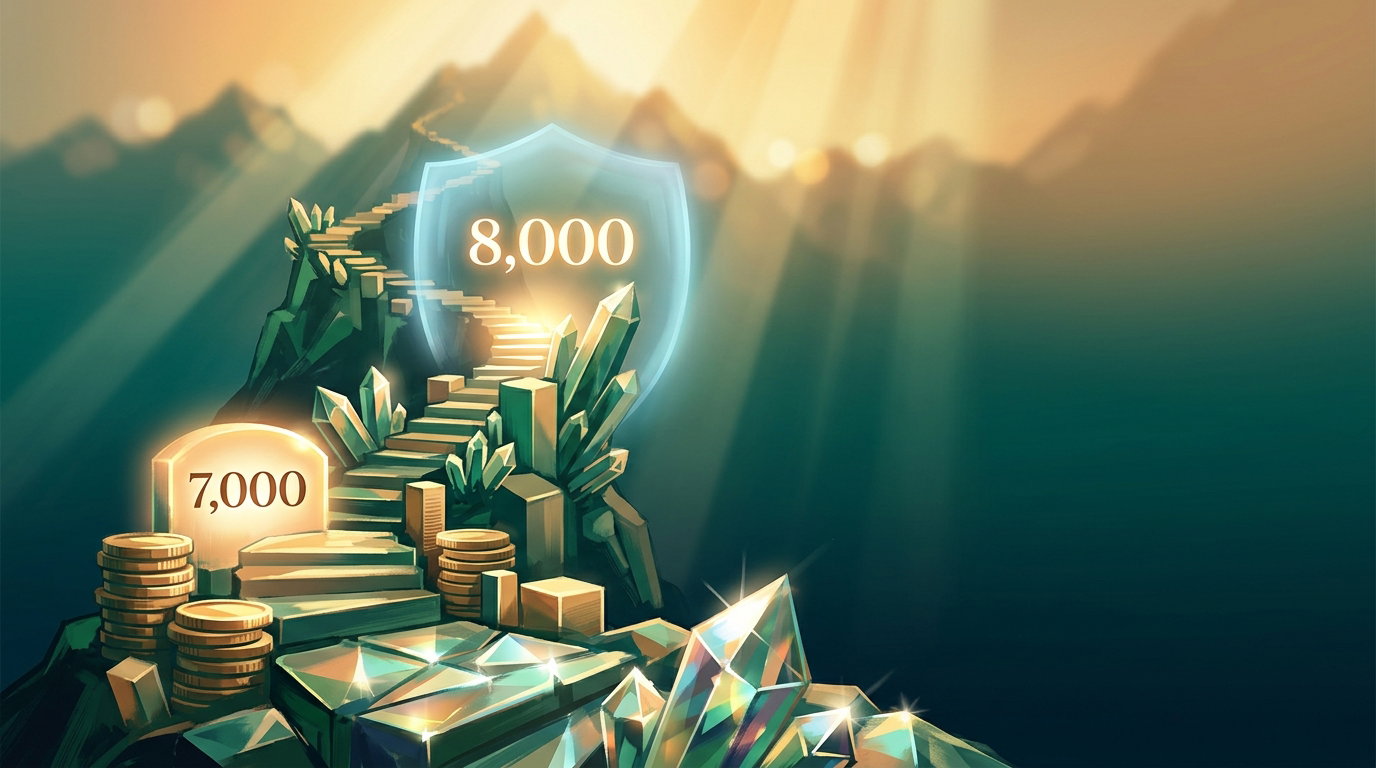
- 2026 IRA contribution limit: $7,000 (under 50) or $8,000 (50+ catch-up)
- Roth IRA income phase-out starts at $150,000 (single) and $236,000 (married filing jointly) for 2025 — verify 2026 thresholds when the IRS publishes them
- Traditional IRA contributions may be tax-deductible depending on income and whether you have a workplace retirement plan
- If your income exceeds Roth limits, the backdoor Roth IRA strategy lets you contribute indirectly
2026 IRA Limits at a Glance
Join ChooseFI free
Save your tools, picks, and progress.
Takes 30 seconds
If you're building toward financial independence, the IRA is one of your most important tax-advantaged tools. But the IRS limits how much you can contribute each year — and those limits come with income-based rules that determine whether you can contribute to a Roth IRA directly, whether your Traditional IRA contributions are tax-deductible, and how much you can actually shelter from taxes.
Getting this right matters. Contribute too much and you'll face a 6% excise tax on the excess. Miss the income limits and you could trigger unexpected tax consequences. Ignore the rules entirely and you're leaving thousands of dollars in tax savings on the table every year.
This guide breaks down the 2026 IRA contribution limits for both Traditional and Roth IRAs, walks through the income phase-out ranges, explains spousal IRA rules for non-working spouses, and covers the backdoor Roth strategy for high earners who exceed income limits.
2026 IRA Contribution Limits
The IRS sets a single combined contribution limit that applies across all of your IRAs — Traditional and Roth combined. You cannot contribute $7,000 to a Traditional IRA AND $7,000 to a Roth IRA in the same year. The total across all IRAs is capped.
For 2026, the contribution limits are:
- Under age 50: $7,000 total across all IRAs
- Age 50 and older: $8,000 total ($7,000 base + $1,000 catch-up)
These limits are the same whether you contribute to a Traditional IRA, a Roth IRA, or split between both. The catch-up contribution amount ($1,000) is not indexed to inflation and has remained unchanged for years — unlike 401(k) catch-up contributions which adjust annually.
You have until Tax Day (typically April 15) of the following year to make your IRA contributions. This means you can contribute to your 2026 IRA any time from January 1 of 2026 through the tax filing deadline in the following spring. If you haven't maxed out last year's IRA yet, check whether you still have time.
| Category | 2026 Limit |
|---|---|
| Under 50 contribution | $7,000 |
| 50+ catch-up contribution | $8,000 |
| Combined limit (all IRAs) | $7,000 / $8,000 |
| Contribution deadline | Tax filing day (~April 15) |
| Excess contribution penalty | 6% per year |
Find your FI number in 60 seconds
Free calculator shows when you could reach financial independence — plus a savings rate tracker, expense audit, and more.
Roth IRA Income Limits and Phase-Outs
Not everyone can contribute directly to a Roth IRA. The IRS sets income limits that phase out your ability to contribute as your Modified Adjusted Gross Income (MAGI) rises. If your income exceeds the upper threshold, you cannot make direct Roth IRA contributions — but you can still use the backdoor Roth strategy.
For 2025, the Roth IRA income phase-out ranges are:
| Filing Status | Phase-Out Begins | Phase-Out Ends (No Direct Contribution) |
|---|---|---|
| Single / Head of Household | $150,000 | $165,000 |
| Married Filing Jointly | $236,000 | $246,000 |
| Married Filing Separately | $0 | $10,000 |
Within the phase-out range, your allowed contribution is reduced proportionally. For example, if you're single with a MAGI of $157,500 (halfway through the $150,000-$165,000 range), you can contribute roughly half the normal limit. Verify the 2026 thresholds when the IRS publishes its annual inflation adjustments.
Married filing separately is the toughest situation — the phase-out starts at $0, meaning virtually any income eliminates your ability to contribute directly to a Roth IRA if you file separately while living with your spouse.
Traditional IRA Deduction Income Limits
Anyone with earned income can contribute to a Traditional IRA regardless of income. However, whether that contribution is tax-deductible depends on two factors: your income and whether you (or your spouse) are covered by a workplace retirement plan like a 401(k).
If You Have a Workplace Retirement Plan
If you're covered by an employer plan, the Traditional IRA deduction phases out based on income. For 2025:
| Filing Status | Full Deduction Below | Partial Deduction | No Deduction Above |
|---|---|---|---|
| Single / Head of Household | $79,000 | $79,000-$89,000 | $89,000 |
| Married Filing Jointly | $126,000 | $126,000-$146,000 | $146,000 |
If Your Spouse Has a Workplace Plan (But You Don't)
If you don't have a workplace plan but your spouse does, you face a separate, more generous phase-out range. For 2025, the deduction phases out between $236,000 and $246,000 MAGI (married filing jointly).
If Neither Spouse Has a Workplace Plan
Your Traditional IRA contribution is fully deductible regardless of income. No phase-out applies.
Start Your FI Journey Today
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
Create a free account to get started
Spousal IRA Rules — Contributing for a Non-Working Spouse
One of the most overlooked IRA rules: you can contribute to an IRA for a spouse who has little or no earned income. This is called a spousal IRA, and it's especially valuable for families where one spouse stays home with children or is between jobs.
The rules are straightforward:
- You must file a joint tax return
- The working spouse must have enough earned income to cover both contributions
- Each spouse gets their own $7,000 ($8,000 if 50+) contribution limit
- The spousal IRA is owned entirely by the non-working spouse — it's their account
This means a married couple filing jointly can contribute up to $14,000 ($16,000 if both are 50+) even if only one spouse has earned income. The spousal IRA is subject to the same Roth income limits and Traditional IRA deduction rules as any other IRA.
For FI seekers, spousal IRAs are a powerful way to double your tax-advantaged space during periods when one spouse takes a career break, pursues education, or focuses on caregiving.
The Backdoor Roth IRA — When You Exceed Income Limits
If your income exceeds the Roth IRA limits, you're not shut out. The backdoor Roth strategy lets high earners get money into a Roth IRA through a two-step process:
- Contribute to a Traditional IRA (non-deductible, since your income is too high for a deduction)
- Convert to a Roth IRA immediately — since the contribution was non-deductible, the conversion is tax-free (or nearly so)
The key rule: if you have existing pre-tax Traditional IRA balances (from deductible contributions or rollovers), the IRS applies the pro-rata rule. This means you can't convert only the non-deductible portion — you must proportionally convert pre-tax and after-tax money together, potentially triggering taxes.
The cleanest backdoor Roth strategy requires having zero pre-tax Traditional IRA balances. If you have old Traditional IRA money, consider rolling it into your 401(k) first to clear the path.
Excess Contribution Penalties
Contributing more than your allowed limit to any IRA triggers a 6% excise tax on the excess amount for every year it remains in the account. Common causes of excess contributions include:
- Exceeding the $7,000 / $8,000 combined limit across multiple IRAs
- Contributing to a Roth IRA while over the income limit
- Forgetting that employer SEP IRA contributions reduce your available Traditional/Roth IRA space in some situations
To fix an excess contribution, withdraw the excess amount plus any earnings before your tax filing deadline (including extensions). The earnings will be taxable, but you'll avoid the ongoing 6% penalty.
Build Your FI Plan
Map your path to financial independence with personalized calculators and milestone tracking.
- Save your progress
- Get personalized next steps
- Access calculators and resources
You're in!
Check your email to get started with your FI Plan.
How to Max Out Your IRA in 2026
A step-by-step action plan for maximizing your IRA contributions.
Check Your Income Against Roth Limits
15 minutesEstimate your 2026 MAGI to determine whether you can contribute directly to a Roth IRA, need to use the backdoor strategy, or should focus on a Traditional IRA.
Pro tip: If you are near the phase-out range, consider deferring income or maximizing above-the-line deductions to stay under the threshold.
Choose Roth vs Traditional (or Both)
10 minutesUnder the income limits? A Roth IRA is usually the best choice for FI seekers — tax-free growth and no required minimum distributions. Over the deduction limits for Traditional? Non-deductible Traditional contributions only make sense as the first step of a backdoor Roth.
Set Up Automatic Monthly Contributions
15 minutesDivide $7,000 by 12 ($583.33/month) and set up automatic transfers from your bank. Automating removes the temptation to skip months.
Pro tip: If you can afford it, front-load contributions in January. Historically, lump-sum investing early in the year beats dollar-cost averaging about two-thirds of the time.
Invest in Low-Cost Index Funds
5 minutesDon't let IRA contributions sit in a money market or cash settlement fund. Invest in a total stock market index fund (VTSAX, FSKAX, SWTSX) or target-date fund appropriate for your timeline.
Consider a Spousal IRA If Applicable
10 minutesIf your spouse has little or no earned income and you file jointly, contribute to a spousal IRA as well. This doubles your household's tax-advantaged IRA space to $14,000 ($16,000 if both are 50+).
Find Your FI Number
See where you stand and model your path to financial independence with our free calculator.

You're in!
Check your email to get started with your FI Number.
Frequently Asked Questions
Yes. The 401(k) and IRA have completely separate contribution limits. You can max out your 401(k) at $24,500 and your IRA at $7,000 in the same year. However, your ability to deduct Traditional IRA contributions may be limited if you have a workplace plan and your income exceeds the deduction phase-out thresholds.
You have two options: recharacterize the contribution as a Traditional IRA contribution before your tax filing deadline, or withdraw the excess contribution plus earnings before the deadline. If you miss the deadline, you'll owe a 6% excise tax on the excess for each year it remains. Many people avoid this risk by using the backdoor Roth strategy from the start.
No. As of the SECURE Act (2019), there is no age limit for contributing to a Traditional or Roth IRA. As long as you have earned income, you can contribute at any age. Before the SECURE Act, Traditional IRA contributions were prohibited after age 70 1/2.
Yes. Self-employment income counts as earned income for IRA purposes. Self-employed individuals can also consider a SEP IRA (up to 25% of net self-employment income, max $72,000 for 2024) or Solo 401(k) for much higher contribution limits. A regular Roth or Traditional IRA can be used alongside these plans.
The deadline for 2026 IRA contributions is Tax Day of the following year (typically April 15). This gives you an extra 3.5 months beyond the calendar year to make or catch up on contributions. Make sure to designate the correct tax year when making contributions after January 1.
Most FI seekers prefer the Roth IRA because withdrawals are tax-free in retirement, there are no required minimum distributions, and contributions (not earnings) can be withdrawn penalty-free at any time. If you expect to be in a higher tax bracket now than in retirement, a Traditional IRA may save more in current taxes. The Roth is generally the better default choice for FI because early retirees often have many low-income years ahead.
The Bottom Line
The IRA is one of the most accessible tax-advantaged accounts available — anyone with earned income can contribute, and the Roth IRA's tax-free growth makes it a cornerstone of the FI strategy. For 2026, contribute up to $7,000 ($8,000 if 50+), choose Roth when possible, and use the backdoor Roth if your income exceeds the limits. Don't forget spousal IRAs to double your household's tax-advantaged space. The contribution deadline extends to Tax Day of the following year, so you still have time if you haven't maxed out yet.
2026 Limit (Under 50)
$7,000
2026 Limit (50+)
$8,000
Best Default Choice
Roth IRA