Login
Financial Independence

Savings rate, FI number, and the path to freedom.

Retirement Strategies

Withdrawal plans, Roth ladders, and early access.

Investing

Index funds, asset allocation, and real estate.

Tax Strategies

Roth conversions, capital gains, and FI tax planning.

Earning More

Career growth, side hustles, and entrepreneurship.

Money Mindset

Beliefs, purpose, and financial psychology.

Health & Fitness

Exercise, nutrition, and mental wellness.

Future Value Calculator

See how your investments could grow over time with compound returns and regular contributions.

Free No signup required Built by ChooseFI
Try an example:

This projection is only the starting point.

$
$
%
$
%

See results in today's purchasing power

%

Increase contributions each year (e.g., with raises)

%

Expense ratio or annual advisory fee

USD ($)

in years

🌿

Your money could generate more than you contribute.

In this scenario, of your ending balance comes from estimated growth, not your contributions.

Total contributed

Estimated growth

From growth

In today's dollars

Year Balance Contributed Growth Growth %

Explore different scenarios

(illustrative examples)

🌴

What does this mean for your financial independence?

At a 4% annual withdrawal rate, a portfolio of could provide approximately:

of portfolio-supported spending

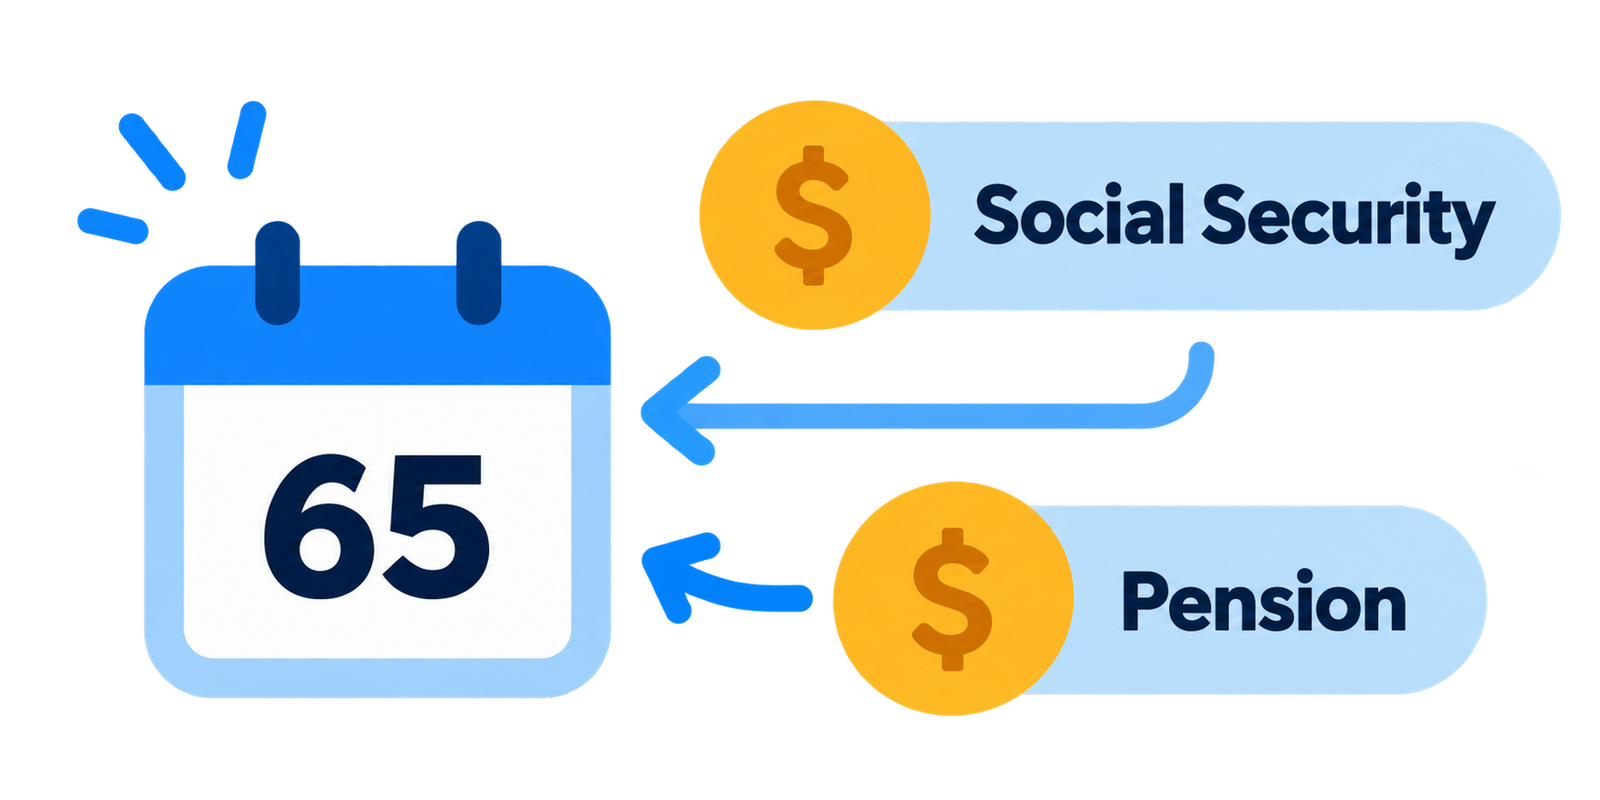
How do Social Security & pensions affect my FI plan?

Add estimated retirement income to see how Social Security and pensions could reduce the amount your portfolio needs to provide.

Turn This Into Your FI Plan

Create a free account to model debt payoff, future income, Social Security, changing expenses and more.

How This Calculator Works

This calculator uses the future value formula with regular contributions to estimate how your investments can grow over time.

Compound growth

Your returns generate their own returns over time, which can lead to exponential growth.

Regular contributions

Adding money consistently can significantly increase your ending balance.

Key assumptions

Results assume a constant annual return and do not predict actual investment performance.

Learn more

See our full methodology, examples, and frequently asked questions below.

Future Value Formula

FV = PV(1 + r/n)nt + PMT × [((1 + r/n)nt - 1) / (r/n)]

  • FV = Future Value
  • PV = Present Value (starting balance)
  • PMT = Payment per period (monthly contribution)
  • r = Annual interest rate (decimal)
  • n = Compounding periods per year (12 for monthly)
  • t = Number of years

This calculator uses monthly compounding (n=12) with contributions added at the end of each period.

Popular Questions

Future value (FV) is the projected worth of an investment at a specific point in the future, based on an assumed rate of return. It matters because it helps you set realistic savings goals, compare investment options, and understand how much your money can grow over time through compound interest.

Compound interest means you earn interest on both your original investment (principal) and on previously earned interest. Over time, this creates exponential growth — your money earns money, and then that money earns money too. The more compounding periods you have, the faster your wealth grows.

For a diversified stock portfolio (like index funds), 7-8% after inflation is a reasonable long-term assumption based on historical S&P 500 returns. For a savings account, use 4-5%. For bonds, use 3-5%. If you want a conservative estimate, use a lower annual interest rate to build in a margin of safety.

Present value tells you what a future amount of money is worth in today's dollars. Future value tells you what today's money will be worth at a future date. They are inverse calculations — a present value calculator discounts future cash flows back to today, while a future value calculator projects current money forward using compound interest. Use "Reach a Goal" mode to solve for present value.

More frequent compounding (daily vs. monthly vs. annually) means interest is calculated and added to your balance more often, which slightly increases your total return. For example, $10,000 at 8% over 20 years grows to $46,610 with annual compounding but $49,530 with daily compounding — a difference of nearly $3,000.

Inflation reduces the purchasing power of future dollars. A dollar 30 years from now will buy less than a dollar today. Toggle the advanced options to enter an inflation rate and see your results in today's dollars. If using 10% nominal returns, a 3% inflation rate gives you roughly 7% real returns.

Yes. The future value formula works for any investment with a consistent rate of return: index funds, bonds, real estate (by estimated appreciation), savings accounts, or CDs. Just use the appropriate expected return rate for each investment type.

That depends on your target FI number (typically 25x your annual expenses) and your time horizon. Use this calculator to experiment: enter your current savings, expected rate of return, and different monthly contribution amounts to see how long it takes to reach your goal. Even $500/month at 8% grows to over $745,000 in 30 years.

Realize the Power of Compound Growth

A future value calculator helps estimate how much your current investments can grow over time by factoring in compound interest. Whether you're saving for retirement, planning a large purchase, or just curious about your investments' potential, understanding future value is essential for making informed financial decisions.

$10,063

$1,000 invested at 8% for 30 years

9 years

Rule of 72: money doubles every

$745K

$500/month at 8% for 30 years

Why Future Value Matters for Financial Planning

Retirement Planning

Estimating how much your savings will be worth in 20 or 30 years helps ensure you're on track to meet your retirement goals. Use the calculator above to model different contribution levels and see how each scenario affects your ending balance.

Choosing the Best Investments

A future value calculator can help compare different investment options to see which one yields the highest returns over time. Try adjusting the annual return between 5% (conservative bonds) and 10% (aggressive growth) to see the range of outcomes.

Setting Financial Goals

Want to buy a house in 10 years? Use the "Reach a Goal" mode to see how much you need to invest each month to hit your target. Even small, regular contributions can make a massive difference in long-term investment growth thanks to compound interest.

Understanding the Time Value of Money

The time value of money is a core financial concept: a dollar today is worth more than a dollar in the future because of its potential to earn interest. This is why starting to invest early — even with a small amount — is so much more powerful than waiting until you have a larger sum. Every year you delay costs you compounding periods that can never be recovered.

How Compounding Frequency Affects Your Returns

Compounding Periods Final Balance Interest Earned
Annual 20 $46,610 $36,610
Monthly 240 $49,268 $39,268
Daily 7,300 $49,530 $39,530
$10,000 invested at 8% annual interest rate for 20 years

Maximizing Your Investment's Future Value

  1. Start investing early. The earlier you start, the more time compound interest has to grow your money. Even small amounts grow significantly over decades.
  2. Contribute regularly. Adding even small regular contributions can supercharge your growth. Increasing your savings rate by $100/month can add hundreds of thousands over a 30-year period.
  3. Aim for higher returns. While higher returns come with greater risk, investing in diversified index funds offers better long-term growth potential than savings accounts.
  4. Watch your fees. Investment fees compound against you just like returns compound for you. Use the advanced options above to see how fees reduce your ending balance.

Common Mistakes to Avoid

Mistake Why It's a Problem Solution
Overestimating returns Leads to under-saving and disappointment Be conservative (5-7% returns)
Ignoring inflation Erodes the real value of savings Use real returns (after inflation)
Forgetting fees and taxes Fees reduce returns significantly Use tax-advantaged accounts

The Bottom Line

The future value calculator makes one thing clear: time and consistency beat everything. Start investing early, contribute regularly, and let compound interest do the heavy lifting. You don't need a massive initial investment — you need the discipline to keep going. Every month you invest brings your FI number closer.
Join ChooseFI free

Save your tools, picks, and progress.

Takes 30 seconds

Built by ChooseFI — Helping people achieve financial independence since 2017.

Methodology: Standard compound interest formula with periodic contributions. Past performance does not guarantee future results.

Reviewed by ChooseFI Editorial Team.

Last updated: September 2026.

Share:

Calculate Your FI Number

See exactly how much you need to retire on your terms. Get a personalized plan in seconds.

Trusted by 30,000+ members

Model pensions, Social Security & life changes

100% free — no credit card required

or

100% free — no credit card required

Account created! Redirecting...

Try searching for

⌘K to open anytime

Where Are You on the Path to FI?

1/3

Step 1 of 3

Which of these sounds most like you?

Scan to get the app

Point your phone camera at the QR code