Key Takeaways
- A will goes through probate (public court process costing 2-7% of estate value), while a living trust transfers assets privately and immediately — avoiding probate entirely for assets held in the trust.
- A revocable living trust costs $1,500 to $5,000 to set up but saves $5,000 to $50,000+ in probate costs and 6 to 18 months of delay — the math favors a trust for estates above $100,000.
- You need a will even if you have a trust — a pour-over will catches any assets not transferred into the trust during your lifetime and directs them into the trust at death.
- Community property states and common law states treat marital assets differently at death — your state's classification directly affects whether a trust or will provides better protection.
What's your FI number? Calculate it in 60 seconds
The one number that changes everything
At a Glance
Key numbers.
How Close Are You to Financial Independence?
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
Head-to-Head Comparison: Living Trust vs Will
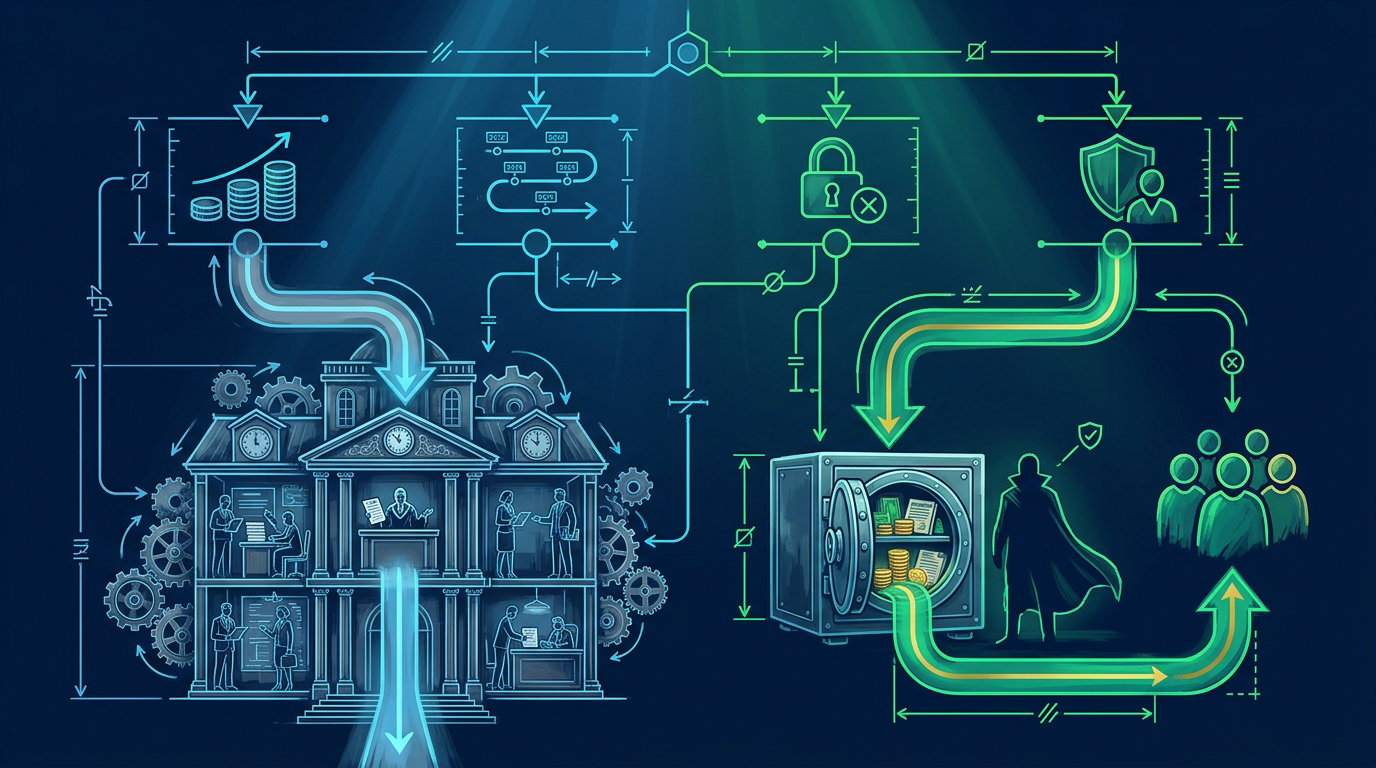
A will (technically a "last will and testament") is a legal document that specifies how your assets should be distributed after your death. It must go through probate — a court-supervised process that validates the will, pays debts and taxes, and distributes assets to beneficiaries. A living trust (specifically a revocable living trust) is a legal entity you create during your lifetime that holds your assets. When you die, the successor trustee distributes those assets according to the trust terms — without court involvement.
| Feature | Will | Revocable Living Trust |
|---|---|---|
| Setup cost | $300-$1,000 | $1,500-$5,000 |
| Goes through probate? | Yes — always | No — assets in trust bypass probate |
| Probate cost | 2-7% of estate value | None for trust assets |
| Probate timeline | 6-18 months (sometimes longer) | Immediate distribution possible |
| Privacy | Public record — anyone can view | Private — no court filing required |
| Incapacity planning | No — only effective at death | Yes — successor trustee manages assets |
| Contest difficulty | Easier to contest in probate court | Harder to contest — no court proceeding |
| Ongoing maintenance | None | Minimal — must re-title assets into trust |
| Effective when | Only at death | During life and at death |
| Covers all assets? | Yes — acts as catch-all | Only assets titled in the trust name |
| Revocable? | Yes — can change anytime | Yes — can amend or revoke anytime |
| Names guardians for children? | Yes | No — requires a separate will |
The critical distinction is probate. In states with expensive or slow probate processes — California, New York, Florida, and many others — a living trust pays for itself many times over. In states with simplified probate procedures (like Texas or Wisconsin for small estates), the cost advantage of a trust is smaller but the privacy and incapacity benefits still apply.
You need both: A trust does not name guardians for minor children (only a will can do that), and a trust only controls assets that have been formally transferred into it. A pour-over will acts as a safety net — it directs any assets not in the trust at your death to pour into the trust, where they are distributed according to the trust terms. The pour-over will still goes through probate, but it ensures nothing falls through the cracks.
Revocable vs Irrevocable Trusts: When Each Makes Sense
The term "living trust" almost always refers to a revocable living trust — one you can change, amend, or dissolve at any time during your lifetime. You remain the trustee, manage the assets as you always have, and pay taxes on trust income using your personal Social Security number. For income tax purposes, a revocable trust is invisible — the IRS treats it as if it does not exist.
An irrevocable trust is fundamentally different. Once established, you cannot easily modify it, and the assets inside it are no longer legally yours. This permanence provides two powerful advantages:
- Estate tax reduction: Assets in an irrevocable trust are removed from your taxable estate. For individuals approaching or exceeding the federal estate tax exemption ($13.61 million per person in 2026), irrevocable trusts can save millions in estate taxes.
- Asset protection: Because the assets are no longer yours, they are generally protected from your personal creditors, lawsuits, and judgments.
| Trust Type | Control | Tax Treatment | Asset Protection | Best For |
|---|---|---|---|---|
| Revocable living trust | Full — you can change or revoke anytime | Pass-through to your personal return | None — assets are still legally yours | Probate avoidance, incapacity planning, privacy |
| Irrevocable life insurance trust (ILIT) | None — trustee controls the policy | Policy proceeds excluded from estate | Yes — proceeds protected from creditors | Removing large life insurance from taxable estate |
| Irrevocable dynasty trust | None after creation | Complex — trust pays its own taxes | Yes — multi-generational protection | Wealthy families transferring assets across generations |
| Charitable remainder trust (CRT) | Limited — income stream to you, remainder to charity | Income tax deduction at creation; income stream taxed | Partial — assets committed to charity | Charitable giving with lifetime income |
| Qualified personal residence trust (QPRT) | Limited — you retain right to live in home for set term | Reduces gift tax value of home transfer | Moderate | Transferring a home to heirs at reduced tax cost |
When Does an Irrevocable Trust Make Sense for FIRE?
The federal estate tax exemption is $13.61 million per person ($27.22 million for married couples) in 2026, but this historically high exemption is scheduled to sunset after 2025, potentially dropping to approximately $7 million per person. FIRE households who have built $3 million to $10 million in net worth through decades of saving and investment growth should monitor this sunset closely. If the exemption drops, irrevocable trusts become relevant at much lower wealth levels.
For most FIRE households with $1 million to $5 million in net worth, a revocable living trust provides the right balance of control, flexibility, and probate avoidance. Irrevocable structures become compelling only when estate tax exposure is real or asset protection needs are elevated.
State-Specific Considerations and How to Decide
Estate planning is governed primarily by state law, and the value of a living trust versus a will varies significantly depending on where you live.
Community Property vs Common Law States
Nine states are community property states: Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin. In these states, most assets acquired during marriage are owned 50/50 by both spouses regardless of whose name is on the title. At death, only the deceased spouse's half passes through their estate plan.
The remaining 41 states follow common law (also called "equitable distribution"). Ownership depends on whose name is on the title. This distinction affects how assets pass at death and whether a trust or will provides better spousal protection.
| State Category | Probate Cost/Complexity | Trust Value | Examples |
|---|---|---|---|
| High-cost probate states | 4-7% of estate; 12-18 months | Very high — trust saves significant money and time | California, New York, Florida, Pennsylvania |
| Moderate probate states | 2-4% of estate; 6-12 months | Moderate to high — trust still provides meaningful savings | Illinois, Ohio, Michigan, Massachusetts |
| Simplified probate states | 1-2% of estate; 3-6 months | Lower financial benefit but privacy/incapacity value remains | Texas, Wisconsin, Montana, Colorado |
| States with small estate shortcuts | Near zero for qualifying estates | Low — simplified procedures may be sufficient | Most states (thresholds vary from $25,000 to $200,000) |
The Decision Framework
Use this framework to determine whether you need a trust, a will, or both:
A will alone is likely sufficient if:
- Your total estate (excluding retirement accounts and life insurance with named beneficiaries) is below your state's small estate threshold
- You live in a state with simple, low-cost probate procedures
- You have no real estate or only one property
- Privacy about your assets is not a concern
A revocable living trust is strongly recommended if:
- Your estate exceeds $100,000 in probatable assets (assets without beneficiary designations)
- You own real estate in more than one state (each state requires a separate probate proceeding — called ancillary probate)
- You live in a high-cost probate state like California, New York, or Florida
- Privacy is important to you
- You want seamless incapacity management without court-appointed conservatorship
- You are pursuing FIRE and want your estate plan to function independently for decades
Add irrevocable trust structures if:
- Your net worth approaches or exceeds the federal estate tax exemption
- You have significant life insurance death benefits that would increase your taxable estate
- You need asset protection beyond what umbrella insurance provides
- You want to establish multi-generational wealth transfer
Remember that a trust only controls assets titled in the trust's name. After creating a trust, you must fund it by re-titling your bank accounts, brokerage accounts, and real estate into the trust. Unfunded trusts — trusts that exist on paper but hold no assets — provide zero benefit. The pour-over will catches stragglers, but relying entirely on the pour-over defeats the purpose because those assets still go through probate.
Top Travel Card
Ready to unlock a world of free travel? Start with the Chase Sapphire Preferred® Card
$95 annual fee | Earn 75,000 bonus points
Best Card for Side Hustlers and Business Owners
Side hustlers! With the Ink Business Preferred® Credit Card you can earn free travel from your business expenses.
$95 annual fee | Earn 100,000 bonus points
Most Flexible Travel Card
The Capital One Venture Rewards Credit Card can be used to offset almost any travel expense.
$95 annual fee | Earn more than $1,000 in Travel Bonuses with a limited-time $300 Capital One Travel stays credit, plus earn 75,000 bonus miles once you spend $4,000 on purchases within the first 3 months of account opening—that's more than $1,000 in travel value
ChooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may receive a commission from card issuers.
How to Get Started
Inventory your probatable assets
Research your state's probate costs and timeline
Decide between will-only and trust-based plan
Hire an estate planning attorney
Fund your trust and verify beneficiary designations
Frequently Asked Questions
Yes. A pour-over will catches any assets not transferred into your trust during your lifetime and directs them into the trust at death. A will is also the only legal document that can name guardians for minor children. Every trust-based estate plan should include a pour-over will.
A revocable living trust prepared by an estate planning attorney typically costs $1,500 to $5,000, depending on complexity and your location. This usually includes the trust document, pour-over will, powers of attorney, healthcare directives, and initial funding guidance. Online trust services cost $200 to $500 but may not address state-specific issues or complex situations.
Yes, and you should be. With a revocable living trust, you serve as both the grantor (creator) and the trustee (manager). You maintain full control over all trust assets during your lifetime. You name a successor trustee who takes over only if you become incapacitated or die.
A revocable living trust does not reduce estate taxes — the IRS treats it as if it does not exist for income and estate tax purposes. However, a trust can be structured with provisions (such as an A/B trust or disclaimer trust) that maximize the use of both spouses' estate tax exemptions. For estate tax reduction, irrevocable trusts are the primary tool.
A revocable trust can be changed, amended, or dissolved at any time. You maintain full control. An irrevocable trust generally cannot be changed after creation, and the assets inside it are no longer legally yours. Revocable trusts provide probate avoidance and incapacity planning. Irrevocable trusts provide estate tax reduction and asset protection.
Without a trust, each state where you own real property requires a separate probate proceeding (called ancillary probate), multiplying costs and complexity. Transferring out-of-state property into a living trust eliminates ancillary probate entirely — the successor trustee can transfer or sell the property without court involvement in any state.
The Bottom Line
The living trust vs will decision is not about which is better — it is about which is better for your specific situation. For estates with more than $100,000 in probatable assets, especially in high-cost probate states, a revocable living trust saves thousands of dollars and months of delay while providing incapacity protection and privacy that a will cannot match. For smaller estates in simplified-probate states, a well-drafted will with proper beneficiary designations may be all you need. Either way, the worst estate plan is no estate plan. More than 60% of American adults have neither a will nor a trust, leaving their families to navigate probate without guidance, pay avoidable costs, and endure unnecessary delays during the most difficult time of their lives.