Given newer research on retirement sustainability—especially work incorporating sequence-of-returns risk (SORR), longerFI horizons, and updated return assumptions such as those discussed in recent analyses of Karsten (ERN) and others —the traditional 25× rule (4% rule) should be rounded up to the **30× rule**. It effectively lowers the withdrawal rate to about 3.333%, which meaningfully improves resilience against early negative market sequences and extends portfolio durability for early retirements that can easily span 35–40+ years. Considering increasing longevity and more uncertain forward returns compared with historical averages, shifting the default planning heuristic from 25× to 30× seems less like being overly conservative and more like aligning the rule of thumb with modern risk realities for the FIRE community. It also makes the math every easier ! Thoughts?
New to Retirement Withdrawal Strategies?
Read our Complete Retirement Withdrawal Strategies Guide →Does anyone else thinks we should adopt the 30x rules instead of 25x?
How close are you to financial independence?
Use our free calculator to find your target number and see how your withdrawal strategy stacks up.
Calculate Your FI NumberReplies (34)
Andrew Pelletier
111 XP7 months ago
I am a fan of a 5% withdrawal rate rather than a 4% mostly because I would be willing to reduce spending or start part time work in the small chance of something going terribly wrong. On average with 4% withdrawal rate you end up like 5x your inflation adjusted starting balance at the end of your lifetime. I dont think I'd be able to see my portfolio cut in half over 2 years and continue making the same 4% (inflation adjusted) withdrawal rate that I started with. It seems natural that people would tighten their belts in a big recession. I can totally get behind a 5% withdrawal rate that only needs 3.33% for minimum fixed expenses though.
Anonymous
8 months ago
It's all about recency bias. Just check the comments, every one things the past decade bonanza is the norm. Just wait until the market is down 40% or 50% again and it will be the 50x rule. I totally agree and actually plan on the 30x. Thank you for bringing that up
Roberto Sánchez
3,299 XP8 months ago
Or, it could be that most people think "the SWR established by the study that considered the great depression, stagflation of the 70s, and the various other market perturbations that affected the markets from the 20s through the 90s, is quite likely to work as advertised." A market that is down 50% hurts, because nobody wants to be selling in a down market. But the point is that the SWR from the Trinity accounts for that (assuming appropriate asset allocations, and so on, and so on).
Anonymous
7 months ago
Fair enough, however BIG ERN's SWR series makes that clear, if your plan is like mine: 47 yrs time horizon, 60% stocks, 2 kids, CAPE at 40, etc, the SWR is actually 2.9% not 4%. Why that is not accounted for by people in the FI community? It always puzzled me
Roberto Sánchez
3,299 XP7 months ago
Because the 2.9% number applies to the "I will never earn another dollar from work and I won't receive social security". If those are both true for you, then you need to think about something lower than 4%, or perhaps even lower than 3%–as you pointed out. But the reality is that most people stumble into hobbies that end up throwing off a bit of income, they start receiving Social Security, they inherit, etc.
JDFI
4,972 XP8 months ago
But the Trinity study did not account for planning horizon longer than 30 years, and the studies that extend duration to 40+ years universally (this includes Bengen, the discoverer of the "4% rule" (though he doesn't call it that)) say 40+ year durations drop SWR by about ½-1%, so the 4% rule should be the 3%-3.5% rule for FIRE timeframes. See
for details.
Roberto Sánchez
3,299 XP8 months ago
I don't disagree with you. However, that is not a result of recency bias, as  @AA40 supposes.
JDFI
4,972 XP8 months ago
Fair enough, but you said "as advertised" - and that means 30 years, according to the actual studies, not FIRE timeframes.
Matt Lammer
671 XP8 months ago
Having FIed 7 years ago and FIREd 5 years ago (with a FI wife who will join me in FIRE likely next year... BEFORE we put our 2 teens through college and increase our empty nest traveling budget), I highly recommend using "25x" for PLANNING purposes. It's directionally accurate and gives breathing room for the many variations to the plan execution that will, inevitably, pop up.
Then, as you approach that, actually do a real assessment of what your "next chapter" lifestyle will REALLY look like, with wiggle room. There WILL, inevitably, be other "chapters" after that with different life goals/expenses/timing. Again, I'd declare "FI" at 25x. A real retirement plan, done with an advice-only, fiduciary CFP can help you sort out what your life/spending goals actually are, stress test your resources against those, and help aim you at the most efficient way to fund your retirement (possibly with other enhancements).
As you approach FI, realize that a 100% Equity portfolio's volatility does realistically mean that you could very well be tracking on FI in just a few years, only to have the market drop by 50%, or stay down for a decade, significantly delaying your FI/FIRE. Do consider "Kitces Bond Tenting" not into Bonds, but your Retirement Phase portfolio in the last few years (decade?) of Accumulation Phase to fairly significantly increase the probability of attaining FI as close to the target number of years left as possible. The absolutely logical best Retirement Phase portfolio, for the vast majority of retirees, would be one optimized for "highest Safe Withdrawal Rate (SWR)". SWR already considers volatility/SoRR and that metric indicates the safety in withdrawing (higher) amounts of money out of your portfolio, annually and in your plan's duration. The Golden Ratio portfolio

is currently #1 for highest SWR (see #1 rank in Column 4, "Safe WR"

) and means that a retiree could reasonably extract about 20-25% MORE money, annually, as safe or safer, than holding a 100% Equity Portfolio (Total Stock Market portfolio)
Total Stock Market Portfolio – Portfolio Charts
or "Classic 60-40" 2-fund portfolio.
Classic 60-40 Portfolio – Portfolio Charts
That's a huge pay raise + booster of probability of plan success. Do look at the PERFORMANCE tables for each of these portfolios, side by side, for comparison, especially for Drawdown and Withdrawal Rates.
We're nearly 100% Golden Ratio at this point, under-drawing the SWR (5% for our duration) for the portfolio for the next 1.5 years (until college). As 1, then 2 kids go to college, and we increase empty nest travel while maintaining our home base, we'll either safely exceed SWR for the few peak years of dual-college (expecting expenses/Withdrawal Rate to drop significantly after) or spread those expenses out over the next few years within SWR - our total expenses dropping off significantly. After getting past our highest expense years of dual early retirement (2x college), we plan on adding risk-based guardrails, shifting our plan Probability of Success to 80% (assessed and adjusted annually) to further increase the amount we Withdraw. While we do plan on spending a good amount on ourselves, we are more looking at these years doing more wealth transfer and non-profit giving, giving as much money as early and often as we can, when they are of highest value to recipients. Our plan is to "Die with Zero" with a reasonable safety margin leftover ( 5 years spending) and transfer as little as possible near the End of Plan vs earlier.
If you're still in Accumulation Phase, don't get hung up on the number so much. It's just a North Star for directional accuracy. It's going to be "a very big number", just focus your time now on improving the systems that will help you get there sooner - automate everything, reduce/eliminate all friction in having as much money as is tolerable shoved into Investing as soon as possible, and increase friction in the Spending side. Our household got to FI by never budgeting - we "anti-budgeted", which is far easier if you have self-discipline or are an inherent "Saver" We simply paid for our retirement immediately, then had targeted amounts of emergency and sinking funds saved for near-term needs, then fixed expenses paid, and the remainder was purely discretionary - just knowing whatever we spent on now took away from another thing/experience we could otherwise do, spending in line with values. It never was "hardship".
adamk
172 XP8 months ago
I stive for FIRE with 3% Safe Withdrawal Rate, but I know I'm super conservative and I also have only 45% of my portfolio in stocks - less than a typical FIRE portfolio. So for most people, I think wouldn't be afraid to go for 4% or maybe 3.5%, especially for those of you living in the US.
Keep in mind that the first years after reaching FI, when the sequence of return risk is the highest, is also the time when it's relatively easier to go back to work in case the market crashes, to earn some extra money and buy more stocks when they are cheap.
FIRESPARKBrenda
254 XP8 months ago
I think most are more likely to die than run out of money (how's that for an opening sentence to really set the mood)
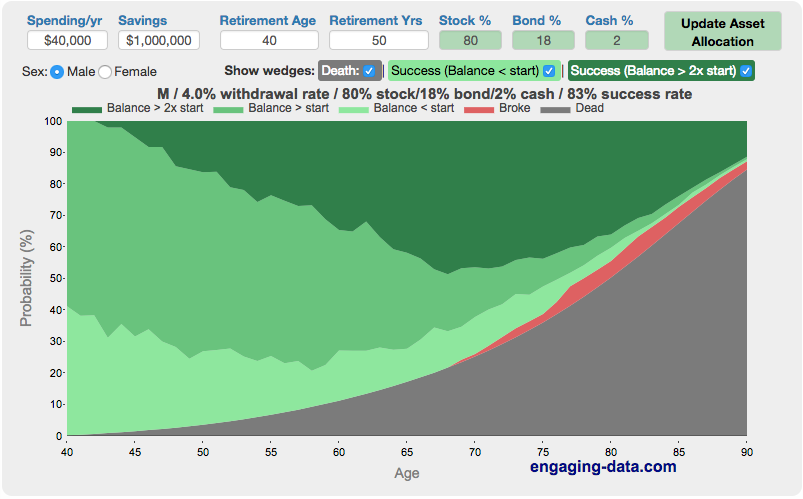
Check out this calculator and look at the flex rates as your guardrails (ability to cut expenses by a % in bad conditions)
I think you also need to back yourself that if you are in this community, who do things a bit fiffjrtto the norm and achieve financial independence, then surely you can work out how not to run out of money without sticking to some strick rule.
JDFI
4,972 XP8 months ago
Interesting graph/tool, but I think it may be a bit misleading, in the sense that different framing may lead to different conclusions.
For instance, using the graph inputs embedded in below link, with 55 retirement years, 60/30/10 portfolio, 10% average tax rate, and 0.5% average expense ratio (these parameters don't appear to be captured by the URL generator, so still have to be input manually):
there is a 44% chance of running out of money at age 80 if you are still alive. Much higher than the 27.4% the graph shows (the probability across all possibilities, including when you are dead). Not longevity risk odds I would take.
The inputs are not unreasonable, and it shows a nearly 50/50 chance of running out of money if you live only until 80, which is in the range of normal life expectancies in the US.
For context,
Dorito
277 XP8 months ago
I love that chart!!! The gray area looms menacingly compared to the red area.
Trust your future self to adjust. You don't have to lock in one rule today for the entire rest of your life.
ScarletsPop
93 XP8 months ago
Here's my take: use the 25x / 4% rule of thumb as a starting point. Model out some assumptions regarding lifespan, expenses, social security, etc using any of the free or more advanced paid calculators, and go with what makes you feel comfortable in terms of success rate. Build some flexibility into your budget. Make sure when you're calculating your expense-based FI number, you're adjusting your expenses for inflation. For instance, $100k in expenses now will cost more if you're planning to reach FI in 10 years. Personally, from the modeling we've done, we're going for 28.57x projected expenses, which equates to a 3.5% SWR. There's a lot of talk in the community about oversaving and working too many years, etc, but it seems prudent to build some buffers into our plans. The future is unknown and unknowable.
DaveATL
154 XP8 months ago
People have been debating the 4% rule of thumb for as long as the FIRE community has existed.
Am I concerned for a US-based portfolio?... absolutely. CAPE10 is near all-time highs. Private Equity has learned to extract much more value from the stock market than any individuals can achieve. US company competitive advantages in computers, robotics, clean energy and biomedicine are being lost to Chinese companies. New tariffs are increased taxation on low and middle class. US international policy is generating hostility that will result in backlash to US business interests. I could go on-and-on.
The 20-year outlook for a US portfolio seems to be facing more headwinds than at any point since WWII. That said, in any predictions I know I've been wrong more often than right.
So what can one do? Remain flexible in capability and attitude. Getting to 25x of spending gives you all kinds of control and freedom. You can decide what to do when you get there. If you're happy with work and life then continuing for a few more x of spending wouldn't be a problem. Nor would changing work for a lower income more enjoyable or part-time job such that you might only need to do 1% or 2% withdraws while the portfolio grows or recovers from a downturn. Or working for one year out of every three or four for the next decade or so.
If I've learned anything it's the answer to the 25x vs 30x is very personal, and probably not even worth worrying about until your portfolio getting quite close.
BostonFI
5,244 XP8 months ago
This is really a discussion of risk mitigation. Under-spending and over-saving are two ways to mitigate risk. The downside of these is that you live more frugally than necessary and work more years than necessary. You probably also die with a lot of unspent money.
Another strategy is to design your portfolio to support a higher safe withdrawal rate. You don't mention the makeup of the portfolio where you would plan a 3.333% withdrawal rate. The makeup of a portfolio matters when talking about SWR because different portfolios support different SWR.
Tyler from Portfolio Charts does a great job in the below article demonstrating how the asset makeup of your portfolio matters for SWR. The classic 60/40 portfolio can support a 4% SWR. The Golden Ratio portfolio can support a 6% SWR.

Del S
2,337 XP8 months ago
For those that are OK being more conservative, absolutely 3.2-3.4% for a 60-year+ time horizon. There's still a lot left on the table if you look at the full distribution; odds of the worst-of-the-worst are pretty low, so taking the tiniest additional chance can help a lot with getting out earlier.
For high earners that are at 70%+ savings rate, if the job isn't awful, an extra 8-24 months of padding isn't bad, either IMO partially since the freedom of having "that much extra" really counts for something.
JDFI
4,972 XP8 months ago
Yes. See member/discussions/1174
Roberto Sánchez
3,299 XP8 months ago
It's important to contextualize the numbers appropriately. The person retiring at age 70 or 75 is in a vastly different position from the person retiring at age 40 or 45 (particularly as it pertains to opportunities to be able to generate income in the future). It is prudent for someone retiring at age 70 or 75 to plan as though there will not be opportunities to earn additional income in the future.
By age 80, the typical retiree is likely to be less physically capable (by a substantial margin) than 5 or 10 years prior. And even if they are still in excellent physical health, I suspect that they are much more likely to face serious age discrimination than someone who is 50 years old.
On the other hand, for a 40 or 45 year old, who is preparing to retire, to assume that there will never be another opportunity to earn a dollar seems rather an absurd proposition. To me, the "we need 30x or 33x instead of 25x" argument is mostly a red herring for this reason. I'm not saying, "be reckless and retire even if your financial situation isn't in order", but rather, "recognize that starting at age 40 or 45, 25x is just about as likely to lead to successful retirement as starting with 30x or 33x".
deleted
613 XP8 months ago
I just look at those numbers as benchmarks. If you’re at 25 times then you should relax and know that you are in a financially strong position. You have plenty of FU money. We have been coast FIRE for 20 years or so and was unaware of this until around 2016. I am 60 and wife 56. Wife works and I work 9 months out of the year. We want to help our 3 kids financially. That is a big reason why we still work. We have to take care of elderly parents, so retiring and traveling are not an option now.
JaneJacquelyn
69 XP9 months ago
I think of the 25 times or the 30 times or the 20 times as a starting point. Once someone gets somewhere into that region, a full financial plan looking at all of one’s goals asset allocation, housing, Social Securityetc. needs to be flashed out.
JDFI
4,972 XP8 months ago
I second Jane's point that if you are in the ballpark and contemplating RE, you should run a complete retirement financial plan either or both by a fee-only fiduciary financial advisor familiar with FIRE, and/or run your full plan through one or more retirement calculators. Options for conventional retirement calculators include those available on large brokerage websites, like Vanguard, Fidelity, Schwab, and for FIRE calculators, I recommend Big ERN's SWR toolkit:
Nathan_B
126 XP9 months ago
these are all just guidelines. Great ideas to keep you on track. You very well be right that 30x is right for you. From what Iv gathered from many of the FI type podcast is that those of us in the community tend to way overshoot our numbers.
For me this endeavor is about maximizing my time and being satisfied with my life when my time comes.
Check out risk based guardrails for drawdown: episode 566 ( I listened yesterday ) it’ll address what you’re talking about
JoeQ17
1,527 XP9 months ago
You're going the wrong way. Bill Bengen's (who came up with the 4% rule) updated research stated that safe withdrawal is closer to 4.7% than 4%. It also accounted for full CPI inflation (which retirees are often CPI minus 1%) and figured a less than ideal portfolio. Add in guardrail withdrawal strategy and 4% gets closer to 6% even with a perpetual withdrawal (infinite years).
So no, not the 30x rule, more like 20x expenses (5% rule) and in reality you can probably get closer to 6%.
JDFI
4,972 XP8 months ago
Sorry, but this misquotes Bengen in two key ways:
- To get SWR up to 4.7% required Bengen to model a more complex specialized ("ideal") portfolio, including overweight midcap, smallcap and microcap stock tilts beyond capweighted total market, among other things. Unless you buy into that portfolio and invest that way, 4.7% is not valid.
- Bengen himself said that longer planning horizons lower SAFEMAX (his term for what we call SWR) here:
In his specific example, SWR dropped 0.3% for 40 year vs 30, and ½% for 50 years, and he's made the general recommendation on podcasts to drop SWR by ~½% for 40+ year planning horizons (e.g. FIRE). All the research in SWR shows that you need to drop SWR beyond the 30 year research results for FIRE timeframes.
I'll also point out that CPI minus 1% isn't a great approximation for very early retirees.
Retirees typical spending patterns below inflation do not generalize to early retirees. Studies on retiree real spending patterns generally don't distinguish early retirees from normal age retirees or don't include early retirees in their data, so they don't tell us whether early retiree spending patterns are similar or different. In searching for studies that identify spending patterns of or relevant to early retirees, I found this, published by the Center for Retirement Research at Boston College:
It shows inflation adjusted consumption drops are primarily tied to health or wealth limitations, and specifically (emphasis added):
consumption for wealthy and healthy households is virtually flat, declining only 0.3 percent a year over their retirement.
Mitchell Nelsen
215 XP8 months ago
"You're going the wrong way" is an apt summary of my response as well.
BOLD TAKE #1: Sequence of returns risk is a mythical boogie man.
The studies that led to the 4% rule and later ones that inch towards a 6% rule ALREADY ACCOUNT FOR sequence of returns risk. The studies were done for every period of time from the worst to the best and find 95%+ success rate. Only a select few terrible years to start retirement did the portfolios run dry.
And, as Brad often points out on the show, YOUR BEHAVIOR WOULD CHANGE in response to down markets. You would not spend as much money as you planned to in those years. And if necessary could find work to bolster your situation.
BOLD TAKE #2: (Math warning)
Once you go beyond 30 years, the change in value you need in your present portfolio is essentially 0.
I am always surprised no one in the FI community talks about the annuity and perpetuity equations (although the 4% rule is basically a perpetuity equation, we just never call it that)
-
The Growing Annuity equation is more complex and relies on a set number of periods:
-
Present value = Cashflow x (1 - (1-i)^-n) / i
where i is the rate of interest aka return and n is the number of periods. Cashflow is aka payment or in FI case, withdrawal.
-
-
Because of math (if you graph this equation for increasing n, it is eventually flat), at some point, no matter how large you make n, the change in PV is negligible. This give us the Perpetuity equation.
(During the Finance class in my MBA program, if n for the annuity equation was >30 years, we simplified to the Perpetuity equation)
-
Perpetuity equation:
- Present value = cashflow / return less inflation. PV = C / (R-g).
- I think it is fun to estimate how much money I could withdraw every year (C) by multiplying the PV of my portfolio by estimated return better than inflation. For example, I have ~$150,00k right now (28 yo Male). Assuming I gain 8% and inflation is 2%...150k*.06 = $9000/yr or $750/mo
- This is effectively using a 6% rule.
- Because of the perpetuity equation, I believe the 4% rule means I only anticipate my returns to beat inflation by 4% over time. I anticipate better returns than that.
Besides the math, who the heck knows what will happen in the next 5 years, let alone the next 30 or beyond.
NOT SO BOLD TAKE:
Do what is best for you!
We all have different risk appetites and personal situations in regards to family, geography, ability to work again, etc. etc.
JDFI
4,972 XP8 months ago
To avoid ambiguity, the 4% rule is not an annuity (you didn't actually say it was), because it is not insured, and returns are not contractually guaranteed. "Past performance is not a guarantee of future results".
The perpetuity equation for annuities is not applicable to historic worst case returns after only 30 years. All the rigorous research on historic worst case returns (and there are a few studies) show that near asymptotic SWR doesn't happen until around 40+ years, but by then SWR has dropped at least 0.3%-1% (depending on the specific research) compared to 30 year duration.
Anonymous
8 months ago
nope. Just ask Karsten and you'll get the real deal few people consider - VALUATION . CAPE10 is at 40 for God sake!!
JDFI
4,972 XP8 months ago
In case anyone reading above wants to know what the reference to Karsten is about, see
The Safe Withdrawal Rate Series - Early Retirement Now.
And specifically CAPE10 and valuations, you can search for CAPE and valuation in the above URL.