Login
Financial Independence

Savings rate, FI number, and the path to freedom.

Retirement Strategies

Withdrawal plans, Roth ladders, and early access.

Investing

Index funds, asset allocation, and real estate.

Tax Strategies

Roth conversions, capital gains, and FI tax planning.

Earning More

Career growth, side hustles, and entrepreneurship.

Money Mindset

Beliefs, purpose, and financial psychology.

Health & Fitness

Exercise, nutrition, and mental wellness.

Living Off the 4% Rule | Marla Taner
Investing
Ep. 560 · · 1h 0m 43s

Living Off the 4% Rule | Marla Taner

Retired since 2013 using the 4% rule through multiple market crashes. Success comes from pressing "sell" one time — the psychology, not the math.

Hosted by Brad Barrett · Guest: Marla Taner
0:00 / --:--

ChooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may earn compensation from card issuers when a customer clicks on a link, when an application is approved, or when an account is opened. Opinions, reviews, analyses & recommendations are the author's alone, and have not been reviewed, endorsed or approved by any of these entities. American Express is a ChooseFI advertiser.

Marla Tanner reached financial independence in 2013 and has lived off the 4% rule ever since — through bull markets, bear markets, and a global pandemic. She recently ran the numbers on both her actual experience and a worst-case scenario retirement starting at the peak before 2008. Both outcomes? More than comfortable. Her journey challenges the anxiety many savers face when it's time to flip the switch from accumulation to spending.

Timestamps:

  • 00:01:26 – Marla's Background
  • 00:02:04 – Living off the 4% Rule
  • 00:09:39 – Psychology of Retiring Early
  • 00:24:33 – Managing Withdrawals
  • 00:25:51 – Market Timing and Cash Strategy
  • 00:28:46 – Travel Rewards
  • 00:49:10 – Lessons Learned
  • 01:00:17 – Conclusion

Key Topics:

How Close Are You to Financial Independence?

Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.

  • 4% Rule in Practice: Marla retired in 2013 and has successfully navigated financial independence using the 4% rule through various market conditions (00:02:04).
  • Psychology of the Transition: Shifting from saver to spender poses psychological challenges — addressing identity and self-worth beyond work (00:50:21).
  • Cash Cushion Strategy: Keeping two years of expenses in cash provides peace of mind during market volatility (00:25:51).
  • Reassessing Fixed Expenses: Many costs assumed to be fixed are actually negotiable or adjustable (00:43:12).
  • Travel Rewards: Marla maintains an abundant travel lifestyle through strategic use of travel rewards (00:28:46).

Resources:

  • Camp Mustache Presentation: Camp Mustache (00:15:22)
  • Related Episode: Episode 77 – Advanced Travel Rewards with Marla Tanner

Notable Quotes:
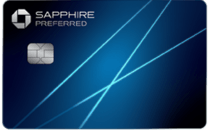
Top Travel Card

Ready to unlock a world of free travel? Start with the Chase Sapphire Preferred® Card

$95 annual fee | Earn 75,000 bonus points
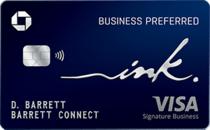
Best Card for Side Hustlers and Business Owners

Side hustlers! With the Ink Business Preferred® Credit Card you can earn free travel from your business expenses.

$95 annual fee | Earn 100,000 bonus points
Most Flexible Travel Card

The Capital One Venture Rewards Credit Card can be used to offset almost any travel expense.

$95 annual fee | Earn more than $1,000 in Travel Bonuses with a limited-time $300 Capital One Travel stays credit, plus earn 75,000 bonus miles once you spend $4,000 on purchases within the first 3 months of account opening—that's more than $1,000 in travel value

ChooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may receive a commission from card issuers.

  • "Success in FI hinges on the ability to confidently sell your investments when the time comes." (00:02:28)
  • "The psychology is so much less about the money and so much more about who we think we are." (00:50:21)
  • "You're never gonna regret this decision. So go ahead, follow your plan and live your best life." (00:54:02)
  • "I would encourage everyone to look at their fixed expenses and think about how fixed they really are." (00:43:12)
Loading transcript...

Comments (2)

Your comment will be posted after signing in
pauln 1 year ago

This was a great episode. What had me a little uneasy is the ‘less lucky’ Marla who started in 2008 as being a worse case scenario. Considering the epic run post 2008, it’s not surprising that even a 30% decline was but a blip.

I wonder what a scenario of someone pulling the plug in the 70’s would look like? But who knows, maybe QE is the new normal and stocks will never stagnate or go down an extended amount again.

Paul

Csyke 1 year ago

Enjoyed the show. Love the real life case studies demonstrating success. 🙂

The show got me to thinking, however, about how great it would be to also do an episode or two or more with families who are working on FI or who have achieved FI who have done so while raising 3 or more kids to adulthood. Bonus points for examples where maybe one spouse was more into (or maybe way more into) FI than the other one and tips on how they got on the same page and got to FI together. Bonus points if they have multiple kids they are putting through or put through college. It would be great to hear their specifics for success.

When I listened to today’s episode it reminded me that my savings is FI for retiring right now and I’d love to quit my job tomorrow and take off and travel- but I have 2 kids in college and one more in high school and my annual spending number is too high relative to my savings number until I get the kid costs/college costs off my annual expense number. I think I’ll be safely FI in 2 years (at 56) when my oldest 2 are out of college -but without kids and the compromises of marriage I would have been FI several years ago in my mid to late 40s at the latest.

Thanks for listening and hope you can make a couple podcasts like this.

2
Jud3579 1 year ago

Csyke

My wife and I have been FI for 7 years, just dropped our 18 yr old off at U Michigan. Our yearly expenses are in the low 6 figures. We started at around a 6-7% withdrawal rate but were all in Index funds and a home bought with cash. It was a rocky emotional ride the first few years but even with the tuition add this year (no loans, no aide) we are growing more than we are spending (our pot has effectively doubled in 7 years).

Getting on the same page took a lot of talking, reviewing plans, looking at the actual in and out data, and genuine effort to address hopes and fears, versus confidence and concerns.

Many of our peers are spending more or living in bigger, newer houses as they have income they feel justifies it. There's a different mentality required when your income is coming from your own holdings. It's like the difference in a company where you're the owner versus a manager spending a budget. The owner spends what is needed and makes impact. The manager may feel like they need to spend to use up the budget.

I'm more than willing to share more, if there are specific areas of interest.

Join the Conversation

Create an account or sign in to post a comment.

Calculate Your FI Number

See exactly how much you need to retire on your terms. Get a personalized plan in seconds.

Trusted by 30,000+ members

Model pensions, Social Security & life changes

100% free — no credit card required

or

100% free — no credit card required

Account created! Redirecting...

Try searching for

⌘K to open anytime

Where Are You on the Path to FI?

1/3

Step 1 of 3

Which of these sounds most like you?

Scan to get the app

Point your phone camera at the QR code