Key Takeaways
- The HSA is the only account in the US tax code with a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses.
- In 2026, you can contribute up to $4,400 (individual) or $8,750 (family) to an HSA — but you must be enrolled in a High-Deductible Health Plan (HDHP) to qualify.
- After age 65, HSA withdrawals for any purpose are penalty-free — you only pay income tax on non-medical withdrawals, making it function like a traditional IRA backup.
- The optimal FI strategy: invest your HSA in low-cost index funds, pay medical expenses out of pocket, save receipts, and reimburse yourself decades later after years of tax-free compounding.
HSA by the Numbers
One of the biggest questions for anyone pursuing Financial Independence, Retire Early (FIRE) is this:
“How will I afford healthcare before Medicare kicks in?”
With the future of U.S. healthcare uncertain, early retirees often face years—if not decades—without employer-sponsored or government healthcare. That’s where Health Savings Accounts (HSAs) come in. They’re more than just a savings vehicle—they’re one of the most powerful, tax-advantaged tools in the FIRE toolkit.
💡 What Is an HSA?
A Health Savings Account (HSA) is a tax-advantaged account designed to help you save and pay for qualified medical expenses.
✅ Key Features of an HSA:
-
Used for qualified medical expenses: doctor visits, prescriptions, dental, vision, chiropractic care, etc.
-
Cannot be used for: insurance premiums, cosmetic surgery, or over-the-counter meds (unless prescribed).
-
Annual contribution limits (2025):
- Individuals: $3,650
- Families: $7,300
- Catch-up (age 55+): +$1,000
-
Eligibility:
- Must be enrolled in a High-Deductible Health Plan (HDHP).
- Minimum deductible: $1,600 (individual) / $3,200 (family)
- Maximum out-of-pocket: $8,050 (individual) / $16,100 (family)
Where Is Your Money Going?
Our free Expense Audit tool breaks down your spending by category and reveals exactly where you can save more. Create a free account to start.
- Category-by-category spending breakdown with visual charts
- Savings potential analysis — see where you can cut without pain
- Track spending month over month and celebrate wins
Free forever — no credit card required
Monthly Spending
$4,180
Potential savings: $620/mo identified
Spending by Category
$4,180
Spending
$620
Can Save
$7,440
Per Year
Preview — create free account to use
🆚 HSA vs. FSA: What's the Difference?
While Flexible Spending Accounts (FSAs) are also meant for healthcare, they come with major limitations:
| Feature | HSA | FSA |
|---|---|---|
| Funds roll over annually | ✅ Yes | ❌ Use it or lose it |
| Account ownership | ✅ You | ❌ Employer |
| Investment options | ✅ Often available | ❌ Not available |
| Portability | ✅ Fully portable | ❌ Tied to your job |
Pro Tip: Even if you change jobs or health plans, you can still use your HSA to pay for medical expenses—tax-free.
Find your FI number in 60 seconds
Free calculator shows when you could reach financial independence — plus a savings rate tracker, expense audit, and more.
How to Maximize Your HSA for Financial Independence
Most people treat their HSA like a medical debit card. Here is how to use it as a wealth-building machine.
Enroll in a qualifying High-Deductible Health Plan
You must be covered by an HDHP to contribute to an HSA. For 2026, a qualifying plan has a minimum deductible of $1,650 (individual) or $3,300 (family) and a maximum out-of-pocket of $8,750 (individual) or $16,600 (family). Compare your HDHP total costs against traditional plan costs — many healthy individuals come out ahead on the HDHP even before counting the HSA tax benefits.
Pro tip: Many employers contribute $500-$1,500 to your HSA if you choose the HDHP. Factor this free money into your plan comparison.
Open an HSA with investment options
Not all HSA providers let you invest. Many employer-provided HSAs only offer a basic savings account earning minimal interest. Look for a provider like Fidelity, Lively, or HSA Bank that offers low-cost index fund investing. You can transfer your HSA to any provider at any time — it is your account, not your employer's.
Pro tip: Fidelity charges zero monthly fees and offers their full brokerage lineup. If your employer HSA has fees or limited options, consider transferring annually.
Max out your contributions via payroll deduction
Contribute the full $4,400 (individual) or $8,750 (family) for 2026. If you are 55 or older, add the extra $1,000 catch-up contribution. Set up payroll deductions rather than manual contributions — payroll deductions bypass FICA taxes (Social Security + Medicare), saving you an additional 7.65% that you cannot get any other way.
Pro tip: The FICA tax savings from payroll deductions is worth $317 (individual) or $635 (family) per year at the 2026 limits. Do not leave this on the table.
Invest in low-cost index funds
Keep a small cash buffer ($1,000-$2,000) for near-term medical expenses and invest the rest in a total stock market index fund. Your HSA should be treated like a long-term retirement account, not a spending account. With decades of tax-free growth, even modest annual contributions can build a six-figure balance.
Pro tip: Align your HSA investments with your overall portfolio allocation. If your 401(k) is heavy on US stocks, consider using your HSA for international or bond exposure.
Pay medical expenses out of pocket and save every receipt
This is the power move that separates the FI community from everyone else. Pay medical bills from your checking account and let your HSA investments compound tax-free. Save every receipt — there is no IRS deadline to reimburse yourself. In 10, 20, or 30 years, you can withdraw the original expense amounts completely tax-free while keeping all the growth.
Pro tip: Create a digital folder for medical receipts. Take a photo of every EOB and bill. Future you will thank present you when you have a stack of tax-free withdrawals waiting.
💸 The Triple Tax Benefits of an HSA
HSAs offer an unparalleled trifecta of tax advantages, making them the only account that delivers tax-free contributions, growth, and withdrawals (when used correctly).
1. Pre-Tax Contributions
- Reduces your taxable income
- Can be made through payroll or direct contributions
2. Tax-Free Growth
- Grow funds via interest or investments
- Unlock investment options like ETFs and mutual funds
3. Tax-Free Withdrawals
- Only applies to qualified medical expenses
- You can save receipts and reimburse yourself years later
⚠️ Non-qualified withdrawals = income tax + 20% penalty (only income tax after age 65)
🔥 Using HSAs to Accelerate Your FIRE Journey
Once you’ve maxed out your IRA and 401(k), the HSA becomes the next most tax-efficient vehicle.
Strategic Use Case: “Reimbursement Later” Strategy
- Pay out-of-pocket for qualified expenses
- Save your receipts
- Let your HSA grow tax-free
- Reimburse yourself in retirement
🧠 Real-Life Example: Phil & Joyce
- Saved in an HSA while paying out of pocket
- Retired at 45, years before Medicare and 401(k) access
- Used saved receipts to create a tax-free income stream
Start Your FI Journey Today
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
Create a free account to get started
💹 HSAs vs. Rising Healthcare Costs
Healthcare costs are surging. Between 2015–2018, premiums rose 28% on private and exchange-based plans, with more insurers exiting the market.
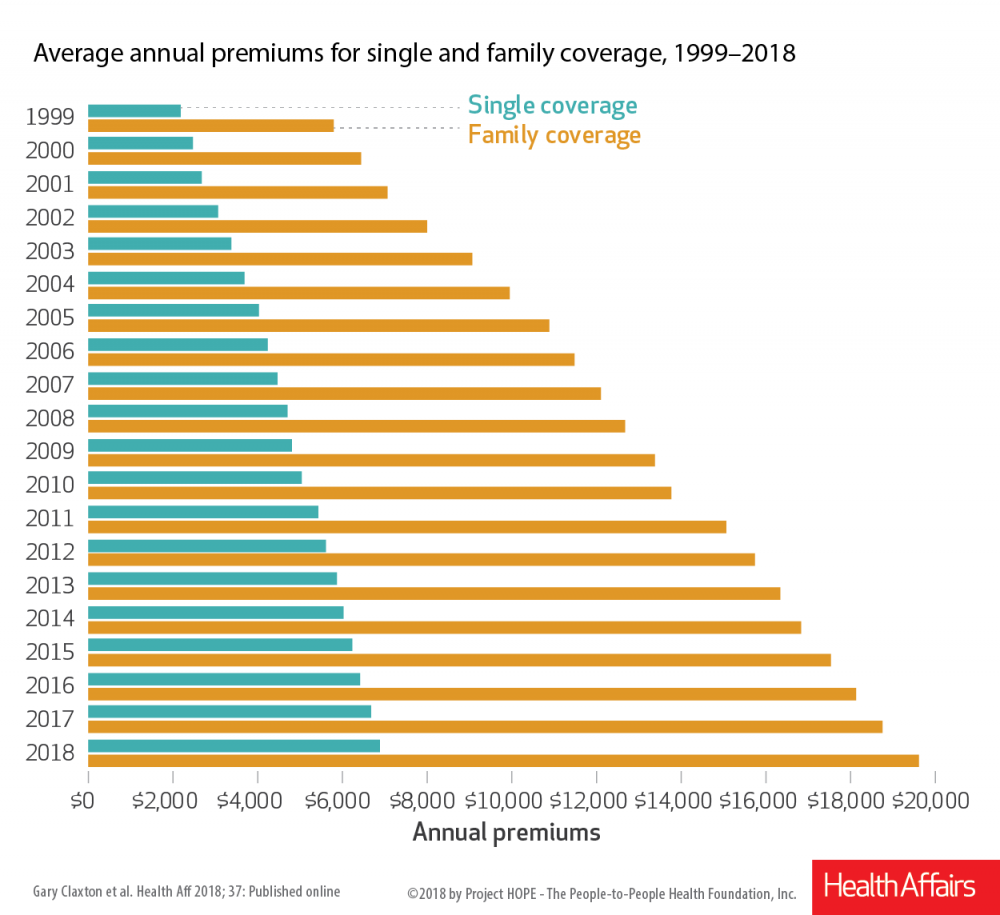 Source: NCSL
Why HSAs Matter:
- Offset unpredictable medical costs
- Delay withdrawals from traditional retirement accounts
- Create a dedicated healthcare safety fund
🧾 Choosing the Right HSA Provider
Not all HSAs are equal—like banks, they vary in fees, tools, and investment options.
What to Look For:
- Low-cost ETF access
- No/minimal fees
- Simple reimbursement process
- Good online interface
💡 Compare before you commit. Hidden fees can erode your growth.
🔚 Final Thoughts: The HSA as a FIRE Power Tool
For early retirees, the HSA isn’t just a health account—it’s a strategic tax shelter and a lifeline for healthcare costs.
🔑 Recap: Why You Should Max Out Your HSA
- 💵 Tax-deductible contributions
- 📈 Tax-free investment growth
- 💳 Tax-free withdrawals for medical expenses
- 🔐 Delayed, flexible use—even in retirement
- 📂 Reimbursement receipts = tax-free income source
Build Your FI Plan
Map your path to financial independence with personalized calculators and milestone tracking.
- Save your progress
- Get personalized next steps
- Access calculators and resources
You're in!
Check your email to get started with your FI Plan.
How Close Are You to Financial Independence?
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
Find Your FI Number
See where you stand and model your path to financial independence with our free calculator.

You're in!
Check your email to get started with your FI Number.
Frequently Asked Questions
The three tax benefits are: (1) contributions are tax-deductible or pre-tax via payroll, reducing your taxable income; (2) investments grow completely tax-free with no capital gains or dividend taxes; and (3) withdrawals for qualified medical expenses are 100% tax-free. No other account offers all three.
For 2026, the HSA contribution limit is $4,400 for individual coverage and $8,750 for family coverage. If you are age 55 or older, you can contribute an additional $1,000 catch-up contribution. These limits include any employer contributions to your HSA.
Yes, but it depends on your HSA provider. Many employer-provided HSAs only offer savings accounts. Providers like Fidelity, Lively, and HSA Bank offer brokerage investment options including low-cost index funds. You can transfer your HSA to an investment-friendly provider at any time.
After age 65, your HSA becomes even more versatile. Withdrawals for qualified medical expenses remain completely tax-free. Withdrawals for non-medical purposes are taxed as ordinary income but incur no penalty — functioning exactly like a traditional IRA. This makes the HSA a powerful retirement backup regardless of your medical needs.
No. Your HSA belongs to you permanently, regardless of employment or insurance changes. If you leave an HDHP, you cannot make new contributions, but your existing balance stays invested and continues growing tax-free. You can still withdraw for qualified medical expenses at any time.
No. The IRS imposes no deadline for HSA reimbursement. You can pay a medical bill out of pocket today, save the receipt, and reimburse yourself years or decades later — completely tax-free. The only requirement is that the expense occurred after your HSA was established.
The Bottom Line
The HSA is the single most tax-efficient account available to Americans on the path to financial independence. Its triple tax advantage — deductible contributions, tax-free growth, and tax-free withdrawals for medical expenses — is unmatched by any 401(k), IRA, or Roth account. The winning strategy is straightforward: enroll in an HDHP, max out contributions through payroll deduction, invest in low-cost index funds, pay medical bills out of pocket, and save your receipts. Over a career, this approach can build a six-figure tax-free medical fund that doubles as a flexible retirement account after age 65.
Family contribution limit (2026)
$8,750
Potential 25-year growth (family max, 7%)
$525K+
Tax advantages vs. any other account
Triple
How Close Are You to Financial Independence?
Build a free FI plan with Coast FI target, savings milestones, and a personalized timeline.