Key Takeaways
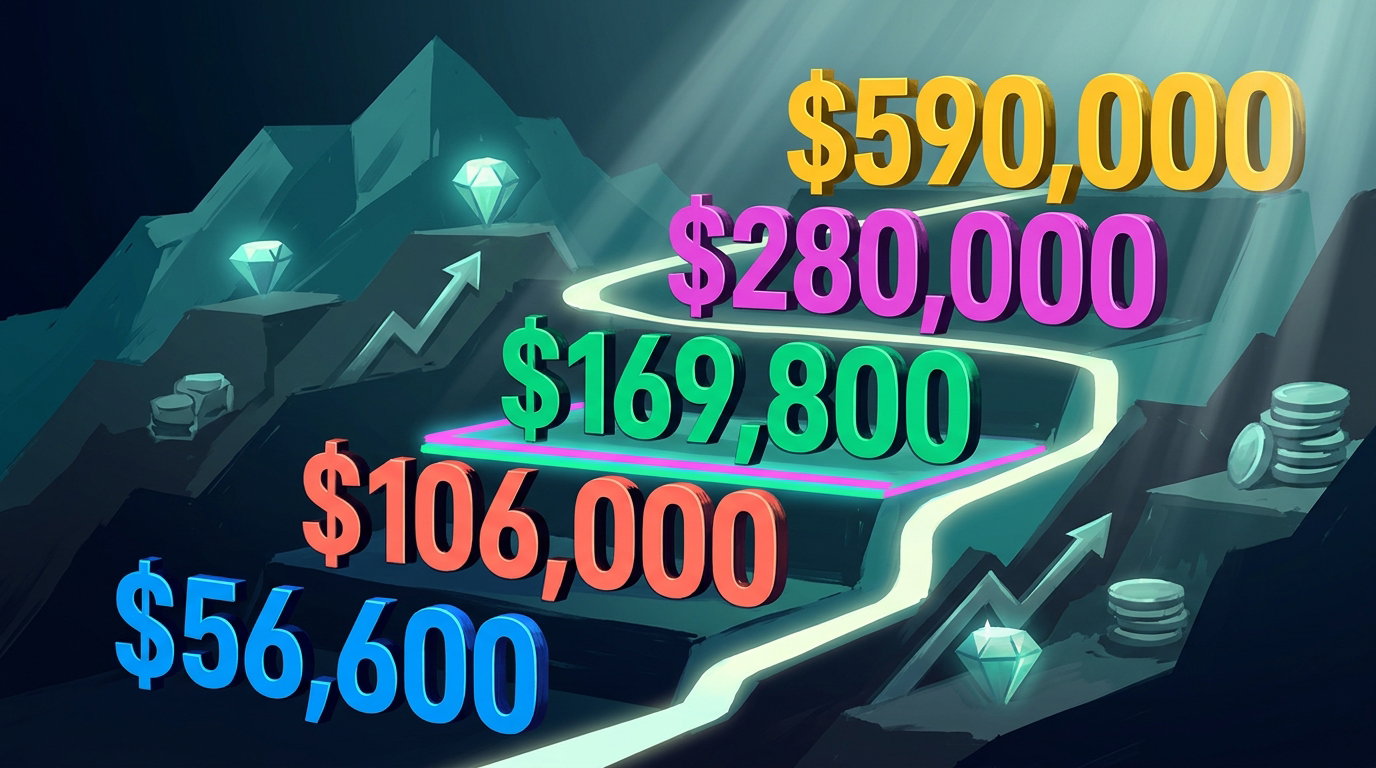
- Pew Research defines upper-income households as those earning more than double the national median — roughly $169,800 or more for a three-person household in 2026
- Upper middle class is not an official category but generally describes households earning $106,000 to $169,800 — the top 20-30% but below the top 5%
- Income class varies dramatically by location — $150,000 qualifies as upper income in rural Mississippi but is solidly middle class in San Francisco
- High income does not equal wealth — many upper-income households have lower net worth than middle-income households with high savings rates, which is why the FI community focuses on savings rate and net worth rather than income alone
What's your FI number? Calculate it in 60 seconds
The one number that changes everything
Income class by the numbers
Where Americans fall on the income spectrum — Pew Research Center 2026 data.
How Close Are You to Financial Independence?
Free calculators, a personalized FI roadmap, and a community of 25K+ on the same journey.
How Income Classes Are Defined
The most widely cited framework for income classes comes from the Pew Research Center, which uses a straightforward formula based on the national median household income. Pew defines three tiers:
- Lower income: Less than two-thirds of the national median
- Middle income: Two-thirds to double the national median
- Upper income: More than double the national median
Using the most recent Census Bureau data with a national median household income of approximately $84,900, the thresholds for a three-person household look like this:
| Income Class | Household Income Range | Share of U.S. Households | Median Net Worth |
|---|---|---|---|
| Lower income | Below $56,600 | 29% | $24,500 |
| Middle income | $56,600 — $169,800 | 52% | $201,800 |
| Upper middle class | $106,000 — $169,800 | ~15% | $465,000 |
| Upper income | Above $169,800 | 19% | $805,400 |
| Top 5% | Above $280,000 | 5% | $1,680,000 |
| Top 1% | Above $590,000 | 1% | $11,100,000 |
The "upper middle class" label is not an official Pew category — it is a colloquial term most commonly used to describe the band between the middle of the middle class and the beginning of the upper class. Think of it as the top quarter of the middle-income range through the entry point of the upper-income range: households earning roughly $106,000 to $169,800.
These definitions are adjusted for household size using an equivalence scale. A single person needs less income than a family of five to achieve the same standard of living. Pew adjusts all income figures to a three-person household equivalent, which is why the thresholds you see in different sources sometimes vary — they may be using different household sizes as their reference point.
How Location Changes Everything About Income Class
National income thresholds are useful starting points, but they obscure a critical reality: the cost of living varies so dramatically across the United States that the same income places you in different classes depending on where you live. Pew Research's cost-of-living adjusted data reveals just how stark these differences are.
A household earning $150,000 in Jackson, Mississippi — where the cost of living is roughly 83% of the national average — has purchasing power equivalent to about $180,700 nationally. That same $150,000 in San Francisco, where costs run about 180% of the national average, has purchasing power equivalent to only $83,300 — technically middle class by Pew's national definitions.
| Metro Area | COL Index | $150K Adjusted Value | Income Class at $150K |
|---|---|---|---|
| Jackson, MS | 83 | $180,700 | Upper income |
| Tulsa, OK | 87 | $172,400 | Upper income |
| Nashville, TN | 97 | $154,600 | Upper middle class |
| Denver, CO | 108 | $138,900 | Middle income |
| Seattle, WA | 149 | $100,700 | Middle income |
| San Francisco, CA | 180 | $83,300 | Middle income |
| Manhattan, NY | 235 | $63,800 | Lower-middle income |
This explains why so many households earning $150,000 to $200,000 in coastal cities feel middle class despite technically being upper-income by national standards. They are not wrong — their lived experience of housing costs, childcare, and taxes genuinely consumes their income at the same rate as middle-income households in lower-cost areas.
Net Worth by Income Class: The Wealth-Income Disconnect
Income class and wealth class are not the same thing. The Federal Reserve's Survey of Consumer Finances reveals that high income does not automatically translate to high net worth. Many upper-income households carry large mortgages, student loans, and car payments that consume much of their earnings. Meanwhile, some middle-income households with high savings rates accumulate substantial wealth over time.
The FI community lives in this gap. A household earning $90,000 that saves 50% of their income and invests consistently will have a higher net worth within 10-15 years than a household earning $250,000 that saves 5%. Income determines your ceiling; savings rate determines your trajectory. This is why ChooseFI focuses on savings rate and investable net worth as the primary metrics of financial progress — not income class labels.
Where FIRE Community Members Typically Fall
The financial independence community occupies a unique position in the income class framework. Survey data from FIRE-focused communities suggests the median household income among FI seekers is roughly $130,000 to $160,000 — placing most in the upper-middle-class to lower-upper-income range. However, successful FI stories span the entire income spectrum, from teachers earning $55,000 to tech executives earning $500,000.
What distinguishes FI community members from their income peers is not what they earn but what they keep. While the average upper-middle-class household saves 8-12% of income, FI-path households in the same income range typically save 40-60%. This results in net worth accumulation that dramatically outpaces their income class peers.
| Metric | Upper Middle Class (avg) | FI Community (median) | Difference |
|---|---|---|---|
| Household income | $130,000 | $145,000 | Similar |
| Savings rate | 10% | 48% | 4.8x higher |
| Annual savings | $13,000 | $69,600 | 5.4x higher |
| Net worth by age 40 | $320,000 | $850,000 | 2.7x higher |
| Expected retirement age | 65 | 45-50 | 15-20 years earlier |
The lesson from this comparison is that income class labels describe your earning power, but they say nothing about your financial trajectory. A middle-income household on the FI path will typically surpass the net worth of upper-income households who spend freely. The FI framework redefines "class" around financial freedom rather than consumption — your class is determined not by what you can afford to buy, but by how many years of expenses your investments can cover.
Household vs Individual Income
Income class definitions use household income, which combines the earnings of all adults in a home. This creates a nuance worth understanding: a dual-income household where each partner earns $75,000 has the same household income ($150,000) as a single-earner household at that level, but the dual-income household often faces higher total costs (two commutes, potentially more childcare) and different tax treatment. When evaluating where you fall, always use your total household income before taxes and compare to thresholds adjusted for your household size.
The distinction between wealth and income is the foundation of financial independence. Your income class describes your present earning power. Your net worth describes your accumulated financial freedom. The FI community's central insight is that you can move from any income class to financial independence by controlling the gap between what you earn and what you spend — and investing the difference consistently in low-cost index funds over time.

Top Travel Card
Ready to unlock a world of free travel? Start with the Chase Sapphire Preferred® Card
$95 annual fee | Earn 75,000 bonus points

Best Card for Side Hustlers and Business Owners
Side hustlers! With the Ink Business Preferred® Credit Card you can earn free travel from your business expenses.
$95 annual fee | Earn 100,000 bonus points

Most Flexible Travel Card
The Capital One Venture Rewards Credit Card can be used to offset almost any travel expense.
$95 annual fee | Earn more than $1,000 in Travel Bonuses with a limited-time $300 Capital One Travel stays credit, plus earn 75,000 bonus miles once you spend $4,000 on purchases within the first 3 months of account opening—that's more than $1,000 in travel value
ChooseFI has partnered with CardRatings for our coverage of credit card products. ChooseFI and CardRatings may receive a commission from card issuers.
How to Evaluate Your Financial Position Beyond Income Class
Calculate your household income and find your income class
Add up all pre-tax income for your household — wages, self-employment, investment income, and any other sources. Compare to the Pew thresholds adjusted for your household size. For a three-person household, middle income is $56,600 to $169,800.
Adjust for your local cost of living
Use a cost-of-living calculator to adjust your income to the national equivalent. A $120,000 income in a city with 130% cost-of-living has the same purchasing power as $92,300 nationally. This adjusted number is a more honest reflection of your class position.
Calculate your net worth and compare to benchmarks
Your net worth — assets minus liabilities — is a better indicator of financial health than income alone. The median net worth for upper-middle-class households is roughly $465,000. If you are above that with a lower income, you are wealthier than your income class suggests.
Determine your savings rate
Divide your annual savings (including employer retirement contributions) by your gross income. The national average is under 5%. The FI community targets 40-60%. Your savings rate is the single most important predictor of when you will reach financial independence.
Calculate your FI number and timeline
Multiply your annual spending by 25 to find your FI number (based on the 4% safe withdrawal rate). Then use your current savings rate and existing net worth to estimate how many years until you reach that number. This timeline matters more than any income class label.
Frequently Asked Questions About Income Classes and Net Worth
According to Pew Research, upper-income households earn more than double the national median household income. For a three-person household in 2026, that threshold is approximately $169,800. However, this varies significantly by location — in San Francisco, you would need roughly $306,000 to have the same purchasing power as $169,800 nationally.
Upper middle class generally describes households in the top 20-30% of earners but below the top 5% — roughly $106,000 to $169,800 for a three-person household. Upper class typically refers to households above $169,800 (top 19%). The top 5% begins at roughly $280,000 and the top 1% at approximately $590,000. These are income-based definitions and do not account for net worth.
By national standards, $200,000 household income places you in the upper-income category (above the $169,800 threshold for a three-person household). However, in high-cost cities like San Francisco, New York, or Boston, $200,000 has purchasing power equivalent to roughly $111,000 to $130,000 nationally — solidly middle class in terms of lived experience.
The Federal Reserve Survey of Consumer Finances shows the median net worth of upper-income households is approximately $805,400. The top 10% of U.S. households by net worth have $1.9 million or more, and the top 1% have $11.1 million or more. Net worth is a more meaningful measure of financial security than income because it reflects accumulated wealth, not just current earning power.
Lifestyle inflation is the primary reason. Many households increase their spending in lockstep with income increases — larger homes, newer cars, private schools, premium vacations — leaving little margin for savings. A household earning $300,000 that spends $290,000 accumulates wealth more slowly than one earning $100,000 that spends $50,000. The FI community calls this the HENRY problem: High Earner, Not Rich Yet.
Pew Research adjusts income thresholds using an equivalence scale based on household size. A single person needs roughly $56,600 to be middle income (the lower bound), while a family of five needs roughly $126,500 for the same standard of living. Larger households need more income to achieve the same class designation because they have more people sharing the resources.
The Bottom Line
Income class labels provide useful context for understanding where you stand relative to other American households, but they are a poor measure of financial health. Plenty of upper-income households are one job loss away from financial crisis because they spend everything they earn, while many middle-income households on the FI path have built net worth that places them in the top 10% of all Americans. The framework that matters most is not whether you are middle class, upper middle class, or upper class — it is whether the gap between your income and your spending is large enough to build financial independence within a timeline that matters to you. Focus on three numbers: your savings rate, your investable net worth, and your FI number. Everything else is a label that describes your present circumstances, not your financial future.